What Are Cash Cycle Procedures?
Cash cycle procedures are documented controls for receiving, recording, safeguarding, depositing, disbursing, and reconciling cash. They make each transaction traceable, separate incompatible duties, and help a small business catch errors or fraud before a problem grows.
Cash management is a critical part of small and medium-sized businesses that rely on a steady, consistent stream of cash from customers paying for goods and services. A practical cash cycle covers more than bills and coins. It includes checks, credit cards, merchant settlements, electronic transfers, deposits, bank accounts, and the records that connect each movement of money to the books. The eight procedures below provide a working structure, followed by a control matrix you can adapt to your team.
What Are Cash Cycle Procedures?
Cash cycle procedures define how money moves through your company from the moment it is received or approved until it appears in the general ledger and bank reconciliation. For a business that depends on a steady stream of incoming cash, the procedures should identify who handles funds, who records transactions, who authorizes disbursements, who reviews exceptions, and which evidence must be retained.
The U.S. GAO Green Book describes internal control as a process that helps an organization achieve objectives related to operations, reporting, and compliance. Although the GAO Green Book formally sets standards for federal agencies, its control principles provide a useful framework for assigning responsibility, documenting transactions, and reviewing results in other organizations.
Cash Policy and Cash Procedures Set Organizational Tone
Cash policies establish management expectations. Cash procedures turn those expectations into repeatable work. When managers require complete records, investigate differences, and update controls when payment methods change, employees see that accuracy and accountability are part of normal operations rather than an exercise performed only before an audit.
Mistakes that are quickly caught and corrected also make the control environment visible. A reviewer can trace a cash receipt to a deposit, a disbursement to an approval, and a bank balance to a reconciliation. Auditors may examine that evidence, but the first purpose is operational: management needs reliable information and a clear record of who completed each step.
Due diligence and transparency involving regular management activity, including creating and updating cash policy and procedures, set a clear signal that professionalism is the standard. Understanding key elements of the business, setting the proper environment for employees, and communicating a clear message about the importance of proper cash management help prevent a sloppy approach from becoming routine.
Cash Management Policy
Many retail and service businesses have multiple people conducting cash transactions throughout the day. A cash management policy should cover cash drawer management, end-of-day closing, credit card and special tender items, cash payouts, deposits, electronic payments, and reconciliation. It should also define approval thresholds, access limits, exception handling, and the records retained for each activity.
IRS guidance identifies deposit information, receipts, invoices, and proof of payment as supporting documents for business records. The IRS recordkeeping guide is a useful starting point for deciding which documents support entries in your books and tax return.
Cash Management Internal Controls
Cash custody creates elevated risk when authorization, handling, recording, and reconciliation are concentrated in one person. Use segregation of duties so the person who receives or pays money is not also the only person who records and reconciles it. Where a very small team cannot fully separate the roles, require a documented owner or manager review of deposits, payment support, bank activity, and reconciliations.
Multiple cash counts by different people provide independent verification. Cash funds should be counted regularly, drawer totals should be compared with register or sales records, and differences should be documented and resolved. Different people should handle cash, checks, and deposits from those who record them in the books whenever staffing permits. These are the foundations of sound cash internal controls.
Adequate control over cash receipts and disbursements is a vital element of the company’s internal accounting controls. Cash handling procedures should minimize cash handling risks by combining data collection and review with typical controls such as second-person reconciliation. Clearly communicated responsibilities also help keep the accounting system intact when duties move between an owner, hired accountant, office manager, or accounting clerk.
Cash Cycle Procedures
The following cash cycle procedures cover distinct control points rather than one rigid sequence. Together they help control cash receipts and disbursements, protect assets, create useful accounting records, and support reliable reporting. The specific roles and approval limits should reflect your transaction volume, staffing, and risk.
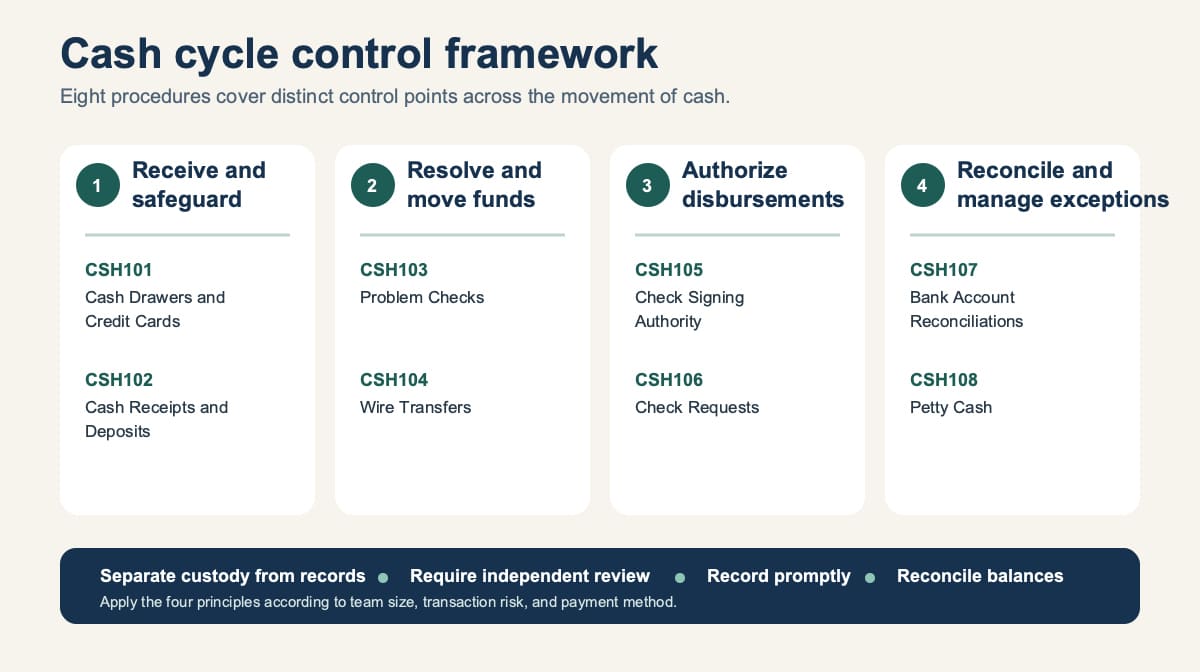
CSH101 Cash Drawers and Credit Cards Procedure
The CSH101 Cash Drawers and Credit Cards Procedure defines control over funds received by cashiers or sales clerks. It should address opening funds, cash receipts, credit cards, refunds, special tender items, cash payouts, drawer access, end-of-day counts, merchant settlement records, and reconciliation with deposits. Record shortages and overages instead of silently adjusting the drawer.
CSH102 Cash Receipts and Deposits Procedure
The CSH102 Cash Receipts and Deposits Procedure describes receiving, identifying, applying, safeguarding, and depositing cash receipts. Develop control totals before funds leave the point of receipt, restrict access while deposits are prepared, and compare the validated deposit with the receipt log and accounting entry. IRS Publication 583 recommends depositing daily receipts into the business checking account and reconciling the checking account each month. See IRS Publication 583 for the small-business recordkeeping context.
CSH103 Problem Checks Procedure
The CSH103 Problem Checks Procedure explains how difficult-to-cash checks are handled before deposit. It should cover unsigned checks, checks marked “payment in full,” stale-dated or postdated checks, discrepancies between words and numbers, and checks returned by the bank. Define who contacts the customer, who approves an exception, how the receivable is restored, and how follow-up is recorded.
CSH104 Wire Transfers Procedure
The CSH104 Wire Transfers Procedure should define initiation, authorization, release, recording, and review for incoming and outgoing transfers. Verify new or changed payment instructions through a known contact method, not the contact information in the change request. The FBI recommends using secondary channels or two-factor authentication to verify requests for changes in account information. The FBI BEC guidance explains why this check matters.
The company may provide additional payment options to customers and vendors, but wire transfers should be treated with special care and accuracy to prevent loss to the company or the receiving party. The procedure should explain the steps necessary for processing wire transfer requests, including the financial institutions involved, required documentation, approval authority, and the response to a suspected unauthorized transaction.
CSH105 Check Signing Authority Procedure
The CSH105 Check Signing Authority Procedure establishes approval limits and identifies authorized signers. The employee entering bills or printing checks should not be the only person approving payment and reviewing supporting documentation. Use a second approver for higher-risk or higher-value payments, and document a compensating management review when team size prevents complete role separation.
CSH106 Check Requests Procedure
The CSH106 Check Requests Procedure defines how manual check requests are prepared, supported, approved, processed, and recorded. A complete request should identify the payee, purpose, amount, account coding, requester, approver, and supporting invoice or receipt. Numbered requests and exception logs make missing or duplicate payments easier to detect.
CSH107 Bank Account Reconciliations
The CSH107 Bank Account Reconciliations procedure describes preparation and review of a monthly bank reconciliation. Compare the bank statement, account register, deposit records, cash receipts journal, and cash disbursements journal. Investigate old outstanding checks, deposits in transit, bank charges, duplicate items, and unexplained adjustments. A person independent of cash receipts and disbursements should review the reconciliation when possible. See how to reconcile a bank statement for a practical walkthrough.
CSH108 Petty Cash
The CSH108 Petty Cash procedure outlines disbursement, documentation, replenishment, and review of a petty cash fund. Set a fixed fund amount and transaction limit, require receipts or written explanations, restrict custody, prohibit personal borrowing, and reconcile cash plus vouchers to the authorized balance before replenishment.
Cash Cycle Control Matrix
Use this worked matrix to assign each control. “Owner” means the person who performs the activity. “Reviewer” means someone who independently approves the transaction or examines the completed evidence.
| Control point | Owner | Independent review | Evidence | Exception trigger |
|---|---|---|---|---|
| Drawer close | Cashier | Shift lead recounts | Register closeout and count sheet | Any shortage, overage, or missing tender |
| Deposit preparation | Accounting clerk | Manager compares control total | Deposit slip and receipt log | Deposit differs from daily receipts |
| Payment release | Accounts payable | Authorized signer | Approved request, invoice, and proof of payment | Changed bank details or approval threshold exceeded |
| Bank reconciliation | Bookkeeper | Owner or controller | Signed reconciliation and exception list | Unexplained item, old check, or late deposit |
Cash Cycle Risks
Common risks associated with embezzlement and fraud in the cash cycle include:
- Cash receipts that are diverted, withheld, recorded late, or recorded for the wrong amount.
- Unauthorized cash disbursements, duplicate payments, or loss of funds.
- Unsupported credits, fictitious expenditures, or estimates used to conceal misappropriated collections.
- Misstated cash balances or falsified bank reconciliations that hide unauthorized transactions.
- Changed wire or ACH instructions that bypass independent verification.
- Card settlements, refunds, or chargebacks that are not matched to sales records and bank deposits.
Develop control totals for cash collections, record transactions promptly and in sufficient detail, and compare deposit records with the general ledger and bank statement. Review cash disbursements with the same discipline applied to receipts. Exceptions should remain open until they are explained, corrected, and approved.
All cash collections should be properly identified, control totals developed, and collections promptly deposited under the documented policy. Transactions should be promptly and accurately recorded, properly accumulated, classified, and summarized in the general ledger. Account records and bank statement balances should be correctly reconciled in a timely manner so that balance misstatement, unsupported credits, fictitious expenditures, or transaction substitution cannot remain hidden.
How Do You Implement Cash Cycle Procedures?
- Map each way cash enters and leaves the business, including cash sales, checks, cards, bank transfers, refunds, and petty cash.
- Assign custody, authorization, recording, and reconciliation roles. Document compensating review where staffing limits separation.
- Set approval limits, deposit timing, access rights, evidence requirements, and exception triggers.
- Train employees on the procedure that applies to their role and require the same records every time.
- Review drawer differences, late deposits, changed payment instructions, unreconciled items, and override activity regularly.
- Update the controls when payment methods, banking access, staffing, or transaction volume changes.
Document these decisions in your accounting procedures manual. Clear procedures make responsibility visible and give reviewers consistent evidence to examine.
Frequently Asked Questions
What is the difference between a cash policy and a cash procedure?
A cash policy states management’s rules, responsibilities, and risk limits. A cash procedure explains the steps, records, approvals, and reviews employees use to follow that policy.
How can a small team separate cash duties?
Separate the highest-risk activities first: custody, payment approval, recording, and bank reconciliation. If one employee must perform more than one role, require a documented owner or manager review of the supporting records and bank activity.
How often should bank accounts be reconciled?
Reconcile every bank account at least monthly. Higher-volume or higher-risk accounts may need more frequent transaction review, especially for unusual transfers, old outstanding checks, or missing deposits.
What records support a cash transaction?
Useful evidence includes receipt logs, register closeouts, deposit slips, merchant settlement reports, invoices, approved check requests, proof of payment, bank statements, reconciliation workpapers, and documented exception approvals.
What control is most important for wire and ACH changes?
Verify new or changed payment instructions through a known contact method and require independent approval before release. Do not rely only on the email, phone number, or link supplied in the change request.
Cash Cycle Procedures are an important part of internal accounting controls because they connect the movement of money with authorization, supporting records, and independent review. Download Free Sample Accounting Procedures to see how editable Microsoft Word templates can help you build an accounting policy and procedure management system.