What Are Internal Controls for Cash Security?
Internal controls for cash security are documented practices that help prevent or detect loss, error, and unauthorized access. They include prompt recording, independent reconciliation, separation of cash custody from bookkeeping, restricted access, physical safeguards, management oversight, and current written procedures.
The logic is similar to locking your car at the local mall. Most people who walk past are honest, but sensible precautions reduce opportunity without assuming that every employee or co-worker is dishonest. The same principle applies to your cash cycle procedures.
Updated October 18, 2026
Internal Controls for Cash Are About Prevention
Good internal controls for cash remove unnecessary opportunity and create evidence that helps you detect mistakes or irregularities. Prevention matters, but it is not the only goal. A control should also make it easier to explain what happened, who handled the cash, which records were created, and who reviewed the result.
The same idea applies to your cash process: use best cash practices and follow proper cash procedures. Improper cash control, poor cash cycle procedures, and weak cash security can create opportunities for error, loss, fraud, or abuse. Proper precautions do not have to be difficult or complex. They should reduce unnecessary opportunity while creating a clear record of each transaction and review.
The GAO Green Book identifies physical safeguards for vulnerable assets, restricted access, complete and timely recording, documentation, reconciliations, and segregation of duties as common control activities. Although the Green Book is written for federal entities, those control principles provide a useful framework that a small business can scale to its own cash volume, staffing, and risk.
Proper precautions for accounting internal controls start with a clear cash process. Decide how cash is received, counted, recorded, stored, deposited, reconciled, and reviewed. Then assign each responsibility and identify the evidence that proves the step was completed.
Proper Internal Controls for Cash Need Proper Records
One foundational control is clear and accurate recording of all cash received and all cash disbursements. Record transactions promptly and retain supporting documents such as register tapes, receipt books, deposit slips, invoices, and approved petty-cash vouchers. A delay in recording creates more room for errors and makes later discrepancies harder to investigate.
The recording element of cash security does not have to be difficult or complex. Simple cash records are more likely to be completed consistently. The IRS recordkeeping guide describes daily summaries of cash receipts, supporting documents, prompt transaction recording, and reconciliation of the business checking account. Your exact records should fit your business, but they must clearly show the source, amount, date, and purpose of each transaction.
With proper records created during cash transactions, regular reconciliation can take place. Depending on your organization, this can include cash drawer reconciliations at the end of a shift or business day, reconciliation before a bank deposit, and a monthly bank statement reconciliation. A separate petty cash reconciliation helps confirm that cash on hand plus approved vouchers equals the authorized fund balance.
These reconciliations may need to occur at several levels. Cash drawer reconciliations can happen at the end of a shift or the business day, a reconciliation can occur prior to a bank deposit, and regular bank statement reconciliations can confirm that recorded deposits reached the bank. The person who does the daily cash deposit reconciliation should not be the one conducting the final monthly bank statement reconciliation.
Management or owner involvement strengthens reconciliation when the review is independent, documented, and followed by action on exceptions. The reviewer should compare the cash records with deposit evidence and bank activity, investigate unexplained differences, and sign or electronically approve the completed review.
Separation of Duties Is a Key Facet
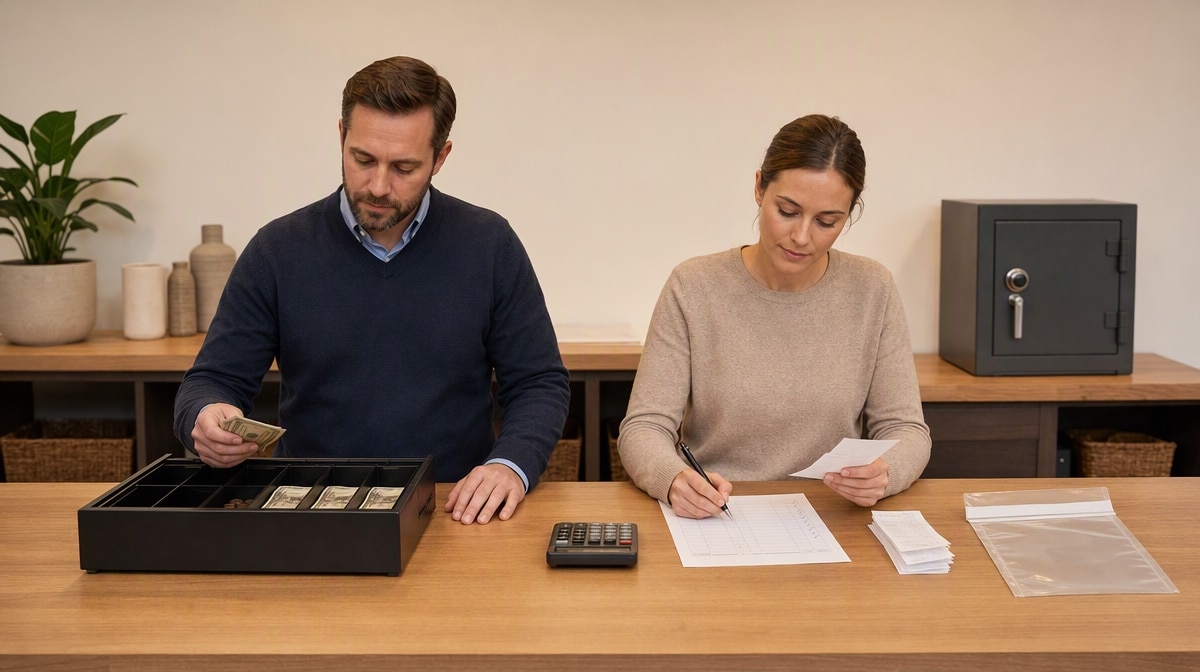
Proper separation of duties is an important cash security tool. Divide authority, custody, recording, and review so one person cannot complete and conceal an improper transaction alone. For example, the person who prepares the daily cash deposit reconciliation should not also perform the final monthly bank statement reconciliation.
Segregation does not eliminate every risk. The GAO guidance notes that collusion can defeat controls, and it recommends alternative control activities when limited staffing makes full separation impractical. In a small business, an owner can review deposit slips against bank activity, receive unopened bank statements, examine reconciliation exceptions, or require a second person for higher-risk cash handling or transport.
Restricting the number of people who can access a cash drawer, safe, petty cash, deposit bag, or related records creates clearer accountability. The goal is not to claim a fixed percentage reduction in fraud risk. The goal is to ensure that authorized access is necessary, traceable, and reviewed.
Example Cash-Control Responsibility Matrix
The following hypothetical example shows how a small business might divide cash responsibilities. Adjust the roles, review frequency, and approval thresholds for your staffing, cash volume, insurance requirements, and risk. When one employee must perform multiple steps, add an independent owner or manager review.
| Cash activity | Primary role | Independent check | Evidence retained |
|---|---|---|---|
| Receive cash | Cashier | Supervisor verifies opening and closing drawer counts | Register tape, numbered receipt, shift count |
| Record the receipt | Bookkeeper or system | Supervisor compares totals with source records | Cash receipt journal, transaction report |
| Prepare the deposit | Cash custodian | Second person confirms count above the policy threshold | Deposit slip, sealed-bag number, count sheet |
| Make or confirm the deposit | Authorized depositor | Manager matches bank confirmation with the deposit record | Validated deposit slip or electronic confirmation |
| Reconcile the bank statement | Person without cash custody | Owner or manager reviews exceptions | Completed reconciliation and exception notes |
| Review exceptions | Owner or manager | Follow-up documented by a responsible control owner | Approval, investigation notes, corrective action |
Use Proper Physical Control for Cash Management
Physical control protects the cash flowing through your business by governing how it is stored, handled, and moved. Reduce the amount exposed to loss when practical, make deposits according to your cash volume and risk, keep cash in a secured drawer or safe, and limit keys, combinations, and access credentials to authorized people.
The obvious rule of thumb behind physical control is to keep no more cash on the premises than the business needs. Make bank deposits as often as necessary for the cash volume and risk. Keep the cash you have on hand in a safe if possible, or at least securely locked. Without good physical control, it is difficult to restrict access and maintain accountability.
For higher-risk amounts or routes, a written procedure may require two people or an insured cash-transport service. These options should follow a risk assessment rather than a universal dollar threshold. The procedure should define who approves the transport, how custody is transferred, which evidence is retained, and how an exception is reported.
Keep cash records protected independently from the cash custodian. Paper deposit evidence can be stored in a restricted location, while digital records need access controls and protected backups. Independent records do not guarantee that fraud or theft cannot occur, but they make it harder to alter the evidence and easier to investigate a discrepancy. A relevant embezzlement prevention manual can help formalize these responsibilities.
Define Cash Processes and Keep Cash Procedures Current
Proper cash controls should be documented in cash procedures as part of your cash management process. A useful procedure names the control owner, the person who performs each step, the required evidence, the reviewer, the exception path, and the records-retention location. This turns a general rule into work that employees can follow and managers can verify.
Keeping cash procedures correct and up to date sends an important message about the due diligence of owners and managers. If the cash process changes, changing the documented cash procedures should be a high priority. Review the control whenever people, responsibilities, banking arrangements, cash handling, or record locations change.
Be sure to understand the cash process and document internal controls clearly. When a drawer, banking method, staffing assignment, point-of-sale system, deposit route, or approval threshold changes, review the procedure and related access promptly. Keeping cash procedures correct and up to date demonstrates due diligence and prevents staff from relying on an obsolete process.
Periodic testing is as important as the written procedure. Select a small sample of cash receipts and deposits, confirm that every required record exists, verify that assigned reviews occurred, and follow unresolved differences to completion. A control that is documented but not performed does not protect the cash process.
Internal Controls for Cash Security
Internal controls for cash security work as a system. Proper cash records support reconciliation. Separation of duties divides custody, recording, and review. Restricted access and physical safeguards reduce exposure. Management oversight resolves exceptions, while current cash procedures keep the process consistent when people or systems change.
The goal is to reduce opportunity, improve detection, and create clear accountability before a loss becomes a larger problem. Review the free policies and procedures for editable Word templates that can help you build a documented policy and procedure management system.