What Are the Uses of Cost Accounting Information?

Every pricing, budgeting, and resource decision starts with a practical question: what did the work actually cost? Cost accounting turns the resources consumed or acquired to perform a service, provide a product, or carry out a project into information management can use.
A cost can be classified by when it is incurred, how it reacts to activity levels, and how it influences a decision. These classifications help Controllers and CFOs control operations, make future plans, evaluate performance, allocate resources, and compare actual costs with budgeted costs.
What Is Cost Accounting?
Basic cost accounting information starts with cost. Cost is a financial measure within an accounting management system that represents resources consumed or acquired in accomplishing a specified purpose, such as performing a service, providing a product, or carrying out a project or program. Cost can be defined in different ways depending on the objectives or information desired.
Cost accounting is a technique or method for determining the cost of a project, process, product, service, or other cost object. The cost may be determined by direct measurement, specific assignment, or systematic and rational allocation. Central to cost accounting is tracing various input costs to the products or services of the company. Cost classifications are based on characteristics such as time incurred, reaction to changes in activity levels, and influence on decision making.
Basis of Cost Accounting
There are two fundamental methodologies of accounting, each with assumptions, constraints, and theories that guide financial recording, reporting, and measurement activities: cash and accrual. The accounting basis determines when the underlying revenue and expense information enters the records that cost accounting uses.
- Cash basis accounting records financial events when cash actually changes hands in an arm’s-length transaction.
- Accrual basis accounting records revenues when earned and records the expenses associated with the revenue when incurred.
The IRS guidance on cash and accrual accounting methods explains the recognition timing for each method. A company should apply the basis appropriate to its reporting and tax requirements consistently and document that basis in its accounting manuals.
How Is Cost Accounting Information Used?
Cost accounting provides essential information to management to control operations, plan future operations, and facilitate the decision-making process. The value is not simply knowing what was spent. Management needs consistent information that explains where costs came from, what activity caused them, and which product, service, program, or project should carry them.
Cost Accounting Control
The Controller should accumulate, distribute, monitor, and evaluate cost information during each accounting period when appropriate. Accounting Management can then use cost information to support operating and financial controls.
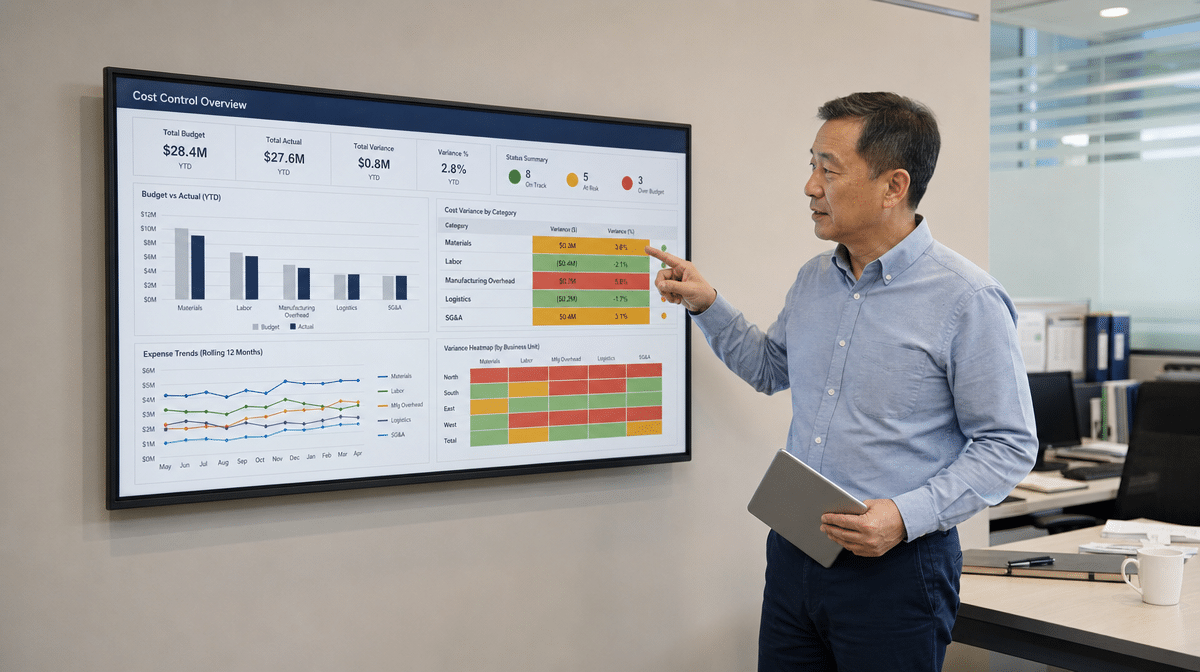
- Make decisions and plan future operations with knowledge of the costs of projects, programs, products, services, and other activities.
- Establish company performance standards based at least partially on past cost history.
- Determine the efficient and effective distribution and use of company resources.
- Support performance evaluation based on actual costs versus budgeted costs.
- Recover costs for products and services provided to other entities.
- Prepare reimbursable work and cooperative agreements.
- Support budget formulation through responses to requests for information.
Cost Accounting Activities
Cost accounting is not applicable to every activity at the same level of detail. For activities that do use cost accounting, the principles should assure that cost accounting information is communicated consistently throughout the company, that reviews of the cost and benefit of specific information use consistent criteria, and that management receives the level of aggregated information required for its decisions.
The Controller is responsible for defining the information needed to meet management, customer-service, reporting, and cost-recovery requirements. The effort required to collect and maintain cost information should be proportionate to the decisions it supports, while the information used for cost recovery should remain complete, consistent, and supportable.
Accounting Cost Timing
Some aspects of cost accounting may be measured in relationship to the time the cost is incurred. In many cases, the measurement time period for a cost is specified in the authorizing documents or contracts for a program. In other cases, the Controller determines which costs will be used for specific purposes and assures that similar activities are treated consistently within the company.
The three common measurements are historical costs, current market costs, and budgeted costs.
- Historical Cost is the cash-equivalent price of goods and services at the date of acquisition. This recorded cost does not change over time.
- Current Market Cost, also referred to as replacement cost in some situations, is the current value of an asset. Depending on whether the asset is tangible or intangible and whether similar assets are available on the open market, current market cost may be measured by replacement cost, reproduction cost, sales value, net realizable value, or net present value of future cash flows.
- Budgeted Cost is the cost management expects to incur to produce a product or provide a service. A standard cost is a predetermined benchmark developed from planned operating conditions and past experience. Comparing actual costs with the predetermined benchmark alerts program managers to areas in which actual costs appear excessive or operating assumptions have changed.
Accounting Cost, Reaction to Changes in Activity Levels
In any period, cost may or may not change in relationship to changes in levels of activity. Based on that relationship, costs are classified as variable, fixed, or mixed costs. Activity measures can include production or service levels, machine hours, or sales in units or dollars. The classification depends on how the total cost for the period, rather than the cost of a single unit of activity, changes when activity levels change.
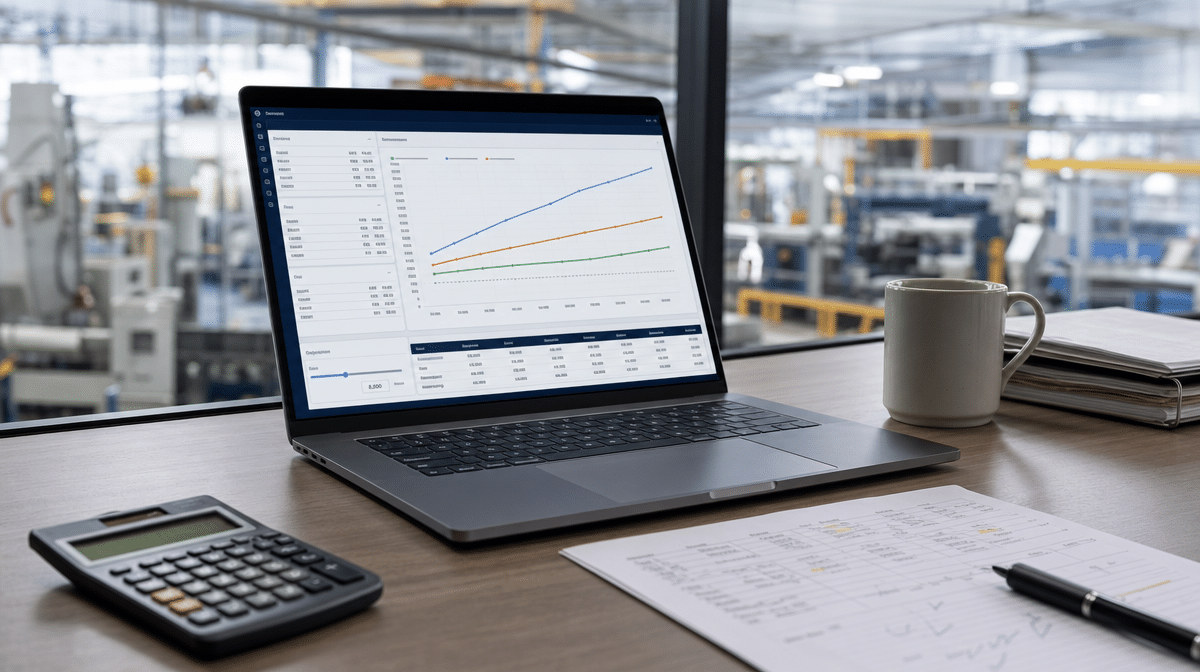
- Variable Costs are costs that vary in total in direct proportion to changes in levels of activity. When total cost varies in direct proportion to activity, the cost per unit is constant.
- Fixed Costs remain constant within the company’s relevant range of activity. A relevant range is the normal operating range in which costs behave according to the way they have been defined.
- Mixed Costs have both a variable and a fixed component. They do not fluctuate in direct proportion to activity, nor do they remain constant when activity changes.
The Controller is responsible for developing cost projections and budgets that identify costs by variable, fixed, or mixed categories. Managers should understand each cost’s behavior and manage it within operating needs rather than assume every cost can be reduced in the same manner. Fixed costs should also be spread fairly over the projects or activities that benefit from them, whether or not those projects incorporate formal cost accounting.
Accounting Cost, Influence on Decision Making
The Controller is responsible for classifying costs as direct or indirect and ensuring that costs are consistently classified in similar situations. This distinction affects product and service costing, project profitability, pricing, budget decisions, performance evaluation, and cost recovery.
Direct costs are costs that can be specifically or readily identified with producing a specific product, providing a specific service, or completing a particular activity. Direct costs can include direct labor, equipment purchased for use on a program, supplies, travel, purchased services, and contractual services. The identifiable portion of base wages and salaries should be charged to the activity that receives the labor.
- Fringe Benefits are allowances and services provided to employees as compensation in addition to wages and salaries, including retirement, health insurance, and life insurance. Fringe benefits may be allocated as a rate applied to direct labor costs. The Controller determines the fringe rate based on labor and fringe costs and may develop separate cost pools when employee groups have significantly different fringe costs.
- Overtime and Premium Pay are charged in the same manner as the regular wage portion of an employee’s earnings for hours identified with a specific activity.
- Other Personnel Costs are charged in the same manner as the related base labor charge. Examples include offsite pay, location allowances, hardship pay, hazardous duty pay, and uniform allowances.
- Equipment Used in an activity for which costs are accumulated may be charged through the full acquisition cost when appropriate or through recovery of a portion of depreciation. The Controller determines whether equipment can be charged in full to a project and, if not, determines the rate and basis for charging equipment usage.
- Other Direct Cost Items can include miscellaneous supplies and materials, equipment rentals, travel, printing and document reproduction, payroll processing services, purchased services, and contractual services consumed exclusively for a specific activity.
Accounting Cost, Indirect
Indirect costs cannot be specifically identified with producing a single product or providing a single service, but they bear a relationship to, result from, or support the product, service, project, or activity.
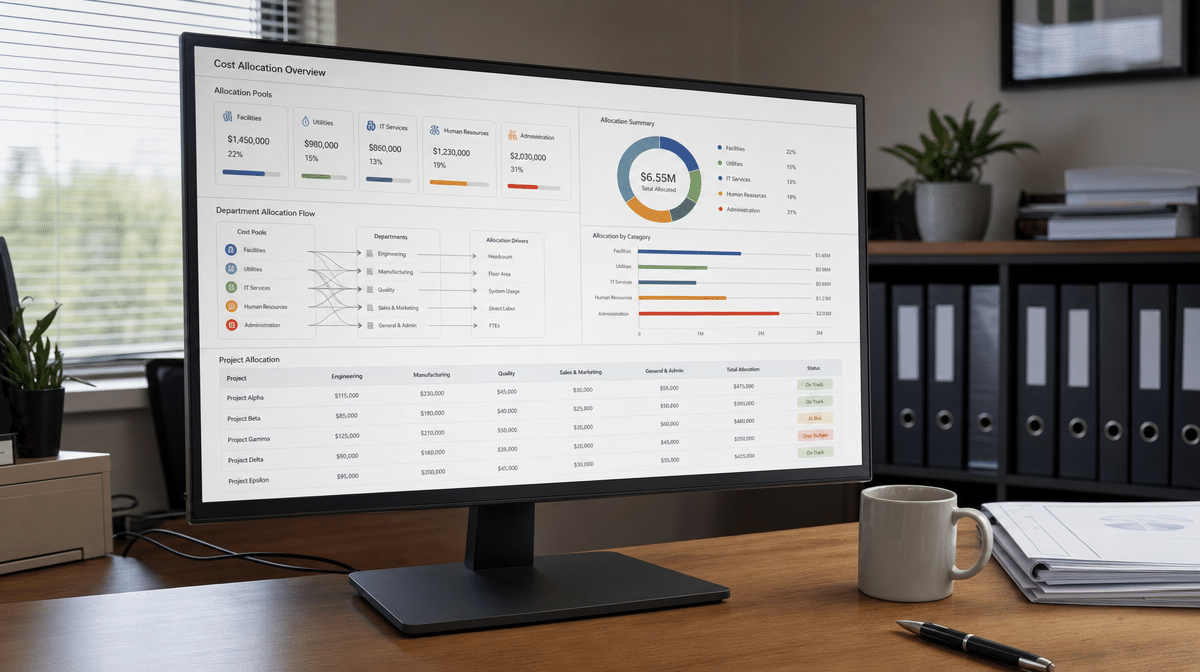
Indirect costs should be accumulated in indirect cost pools, and the Controller should clearly define identifiable cost pools. The Federal Acquisition Regulation’s indirect-cost guidance describes the use of logical cost groupings and allocation bases for contract costing. Even when a company is not subject to those federal rules, consistency and a reasonable relationship between the pool and the benefited activities remain sound cost-accounting principles.
Indirect costs may include the following examples when the item is not directly attributable to a specific activity:
- Space rental and utilities, including telephone expenses.
- Postage, data processing, management, and control.
- Equipment rentals, miscellaneous supplies and materials, and equipment costs not recovered as direct costs.
- Training, employee development, personnel transfers, travel, and time in transit.
- Budget development, program planning, research, and development activities.
- Administrative support such as procurement, contracting, office services, property management, payroll, voucher processing, personnel services, records management, and document control.
- Report preparation and distribution.
- Safety management, including inspection and training.
- EEO and other affirmative action programs.
An indirect cost pool will generally include costs that benefit both cost-recoverable and non-cost-recoverable work, such as Sarbanes-Oxley compliance costs. Even if indirect costs are not allocated to non-cost-recoverable work, the company should use an allocation basis that would fairly distribute the cost pool over all benefited activities. Cost-recovery projects should not be unduly burdened with indirect costs.
How Does Cost Accounting Support Management Decisions?
Cost accounting information helps management improve operational effectiveness, evaluate programs, set prices, prepare budgets, and enhance profitability or reduce costs. It also supports strategic cost management by showing which resources an activity consumes and how cost behavior changes when volume, capacity, or operating assumptions change.
The CFO or Controller is responsible for developing and documenting the allocation method, using a generally acceptable and consistently applied overhead rate based on direct costs, identifiable cost pools, and the cost elements charged to those pools. When the same methods are used for estimating, accumulating, reporting, and evaluating costs, managers can compare plans with actual performance and make decisions from information they can explain and defend.
Frequently Asked Questions
What Is Cost Accounting?
Cost accounting determines the cost of a product, service, project, process, or activity through direct measurement, specific assignment, or systematic allocation. It traces resources consumed to the work that benefits from them.
How Is Cost Accounting Information Used?
Management uses cost accounting information to control operations, prepare budgets, establish performance standards, allocate resources, evaluate actual costs against budgeted costs, and support pricing or cost-recovery decisions.
What Is the Difference Between Cost Accounting and Financial Accounting?
Financial accounting records and reports company transactions for financial statements and other external requirements. Cost accounting uses detailed internal cost information to support planning, control, allocation, and management decisions.
What Are Direct and Indirect Costs?
Direct costs can be specifically identified with a product, service, project, or activity. Indirect costs support more than one activity and are accumulated in cost pools before being distributed using a reasonable allocation basis.
What Are Fixed, Variable, and Mixed Costs?
Variable costs change in total with activity, fixed costs remain constant within a relevant range, and mixed costs contain both fixed and variable components. Understanding cost behavior helps managers forecast how total costs may change as operating volume changes.