What Are Accounting Management Systems?

How familiar are you with the accounting rules and concepts behind your accounting system? If you were more confident in the information generated by your accounting program, you could use it more effectively to run the company, plan cash needs, monitor controls, and prepare for audit questions.
More importantly, do you understand how your Accounting Policies and Procedures connect accounting rules, source documents, software settings, approvals, reconciliations, and internal controls into one working accounting management system?
What Is An Accounting Management System?
An accounting management system is the structured set of policies, procedures, documents, accounting records, software workflows, and internal controls that govern how accounting work is performed. The software matters, but it is only one part of the system. The management system explains who authorizes transactions, which documents support them, how they are recorded, when they are reviewed, and how exceptions are resolved.
Your Accounting policies and procedures manual, associated accounting procedures, and accounting documents establish the practical foundation of your Accounting Management System. When organized correctly, the system improves the effectiveness of accounting operations and strengthens your ability to satisfy auditor requirements. The GAO Green Book sets internal-control standards for federal agencies and explains that certain nonfederal organizations may adopt it as a framework. Its focus on operations, reporting, compliance, and risk provides a useful reference point for a business designing accounting controls.
The risk is that many businesses treat accounting software as if it automatically creates reliable accounting information. It does not. Software can calculate, post, and report, but it cannot decide whether a transaction was properly authorized, whether the source document is complete, or whether a manager reviewed a reconciliation on time.
How Do You Maintain Your Accounting Management System?
In many small and mid-sized companies, maintenance of the Accounting Management System is the responsibility of the Controller/CFO in conjunction with the Accounting Department. In a smaller company, an owner or accounting manager may fill that role. The assigned owner maintains the documents that identify the sequence of accounting processes and, with the appropriate department managers, defines the interactions between those processes.
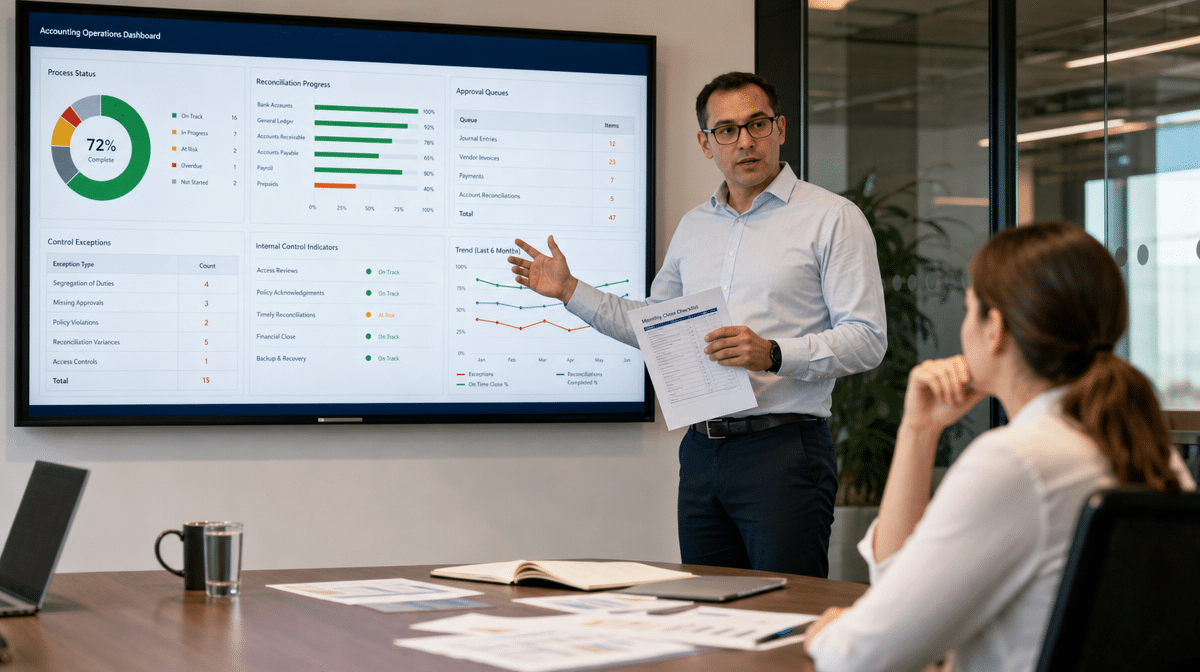
The system should cover management review, staffing and access responsibilities, transaction processing, reconciliations, exception reporting, and control monitoring. Accounting procedures should define the methods needed to ensure that accountability and control of processes are effective. You can find examples in the free sample internal control procedures.
Accounting department managers and the CFO or Controller monitor, measure, and analyze accounting processes. They implement actions necessary to achieve intended results and continual improvement, then review those results at accounting Management Review meetings.
Any financial process that is outsourced and may affect your company’s conformity to requirements must also be controlled. The Controller and appropriate department managers are responsible for defining the methods used to control outsourced processes, outsourced procedures, and the information returned from those service providers.
Why Did Accounting Management Systems Used To Require So Much Documentation?
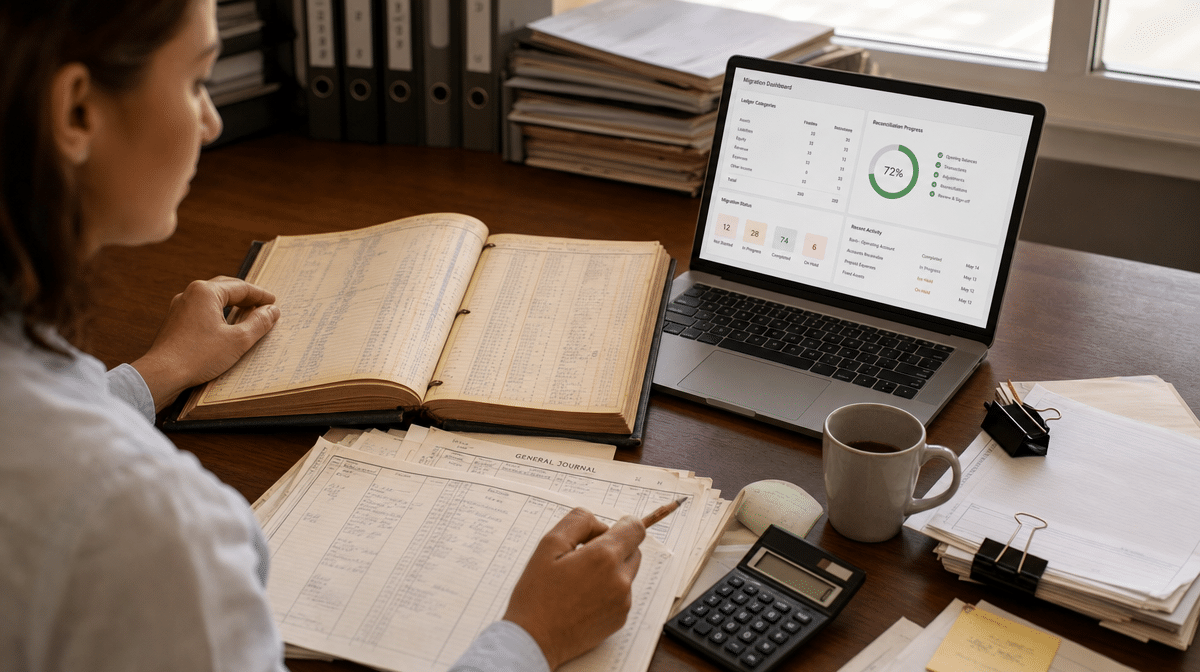
Historically, small and mid-sized businesses faced difficult choices when selecting accounting systems. They could continue with a manual system, purchase or lease a computerized accounting system, or build an automated system. A full manual system might include one-write journals, a cloth-bound general ledger, and tightly controlled forms.
Manual accounting systems were not trivial. They were produced by major firms that provided on-site implementation and training. The systems were well documented because many accounting policies and procedures were built into the regimented use of journals, ledgers, and supporting documents. Internal controls were manual, visible, and heavily dependent on disciplined paperwork.
The alternative was to purchase or lease an automated accounting system. That required another decision: buy a ready-made product or build a custom one. A company often hired a consultant or CPA firm to perform a needs analysis, then selected a commercial multi-module accounting program or hired a programmer to develop a custom system. Historical products such as Solomon, RealWorld, MAS 90, Great Plains, and IBM System/36 environments belong in this context: they illustrate the scale of earlier accounting-system decisions, not current software recommendations.
Those systems required substantial time and money. Even ready-made solutions often needed additional programming to fit a specific company’s processes. For months, consultants, programmers, accounting staff, and managers wrote code, tested workflows, rewrote code, documented processes, and trained users.
Documentation was paramount. Accounting Policies and Procedures, as they applied to the mechanics of the accounting system, were documented as a by-product of installation and implementation. The total cost in hardware, software, outside specialists, and company time could be substantial.
How Have Accounting Management Systems Changed?
Accounting software is now easier to acquire and deploy than the older manual or custom-programmed systems. A business can start with general bookkeeping software such as QuickBooks or use a broader system such as Sage 100, formerly MAS 90. Microsoft Dynamics GP, formerly Great Plains, remains in use as a legacy product, but the official Microsoft Dynamics GP lifecycle lists retirement on January 1, 2030. Cloud accounting, integrations, bank feeds, approval workflows, and dashboards have changed the implementation model, but product availability and support should be verified during every system review.
The accessibility is useful, but it also creates a control problem. Many accounting programs explain user features better than they explain accounting policy. They show where to click, but they do not define who should approve a vendor, what evidence supports an invoice, how a cutoff date is documented, or how management should respond to an exception.
None of these accounting programs replaces supporting accounting policy and procedure documentation. Internal controls still require judgment, review, segregation of duties, and evidence. For companies subject to Sarbanes-Oxley, accounting software alone does not establish compliance or control evidence. Other businesses still need controls suited to their own reporting obligations, risks, and management policies. You can develop accounting policies and procedures yourself from scratch, but this takes time and expertise.
What Accounting Internal Controls Should Be Included?
Accounting internal controls, procedures, and practices are utilized to ensure that:
- Company obligations and costs comply with applicable laws and management policies.
- Assets are safeguarded against waste, fraud, loss, unauthorized use, and misappropriation.
- Revenues and expenditures applicable to company operations are recorded and accounted for properly so reliable financial and statistical reports can be prepared.
- Programs are efficiently and effectively carried out in accordance with applicable laws and management policy.
The COSO internal control framework is a useful reference point because it treats control as a system of related components, including control environment, risk assessment, control activities, information and communication, and monitoring. In a smaller business, that framework still comes down to practical questions: who approves, who records, who reviews, who reconciles, and who follows up when something does not match.
Audit Findings
Managers of the Accounting Management System should promptly evaluate findings and recommendations reported by auditors. They should determine proper actions in response to audit findings, including corrective actions, and complete those actions within established time frames.
The audit resolution process begins when audit results are reported to management. It is completed only after actions have corrected identified deficiencies, produced improvements, or demonstrated that the findings and recommendations are invalid or do not warrant management action.
Accounting Transactions
All accounting transactions and other significant events should be clearly documented, properly classified, and readily available for examination. This standard applies to the entire accounting process or life cycle of a transaction or event, including initiation, authorization, processing, and final classification in summary records.
All transactions recorded or posted into the Accounting Management System should be properly authorized and accurately represent the activity being documented. Both the timing and amount of the transaction should be in accordance with company accounting policies.
Accounting Transaction Authorization
Accounting transactions and other significant events are to be authorized and executed only by people acting within the scope of their authority. Authorization is the principal means of assuring that only valid transactions and events are entered into the accounting system. Modification or adjustment to previously recorded transactions also requires authorization.
Accounting Transaction Timing
All transaction dates recorded in the company accounting system should accurately reflect the date the transaction occurred. Under an accrual method, businesses generally report income when earned and deduct or capitalize expenses when incurred, while cash-method timing differs, as the IRS accounting-method guidance explains. The revenue cycle, processing cutoffs, and period-end closing schedules and procedures should be documented for the method and reporting framework the company uses. Cash sales should be recorded at the time of sale and deposited promptly.
Accounting Transaction Amounts
Prior or related transactions should be checked for conformity with the transaction being recorded. For example, an invoice may be matched to a purchase order or receiving document. Posted transaction amounts should be checked against source documents. Balances with third parties should be verified as appropriate, including debtors, creditors, custodians of investments, and other counterparties.
Accounting Transaction Accuracy
Transactions should be recorded in the accounting system accurately. An approved set of general ledger and subsidiary accounts is maintained for assets, liabilities, revenues, expenses, budgetary accounts, and other accounts. All transactions should be supported by documentary evidence, which becomes part of the accounting records. Error transactions should be reviewed, resolved, and cleared in a timely fashion. Manually determined control totals should be reconciled with recorded results.
Your Accounting Management System is comprised of your Accounting manual, associated accounting policies and procedures, and accounting documents. The system utilizes standard forms and provides control and accountability over those forms. Supervisors should review posted accounting transactions with source documents and processing documents.
What Should Accounting Management Systems Look Like Now?
Modern accounting systems are more accessible than ever, but accessibility should not be mistaken for control. A cloud accounting application can automate bank feeds, invoice routing, approval notifications, and dashboards, but the company still needs documented rules for how those workflows are used.
Accounting Management System Health Check
Use this table during a monthly close review, process walk-through, or software change. A “no” answer identifies a control or documentation gap that needs an owner and a due date.
| Check | Evidence To Review | If The Answer Is No |
|---|---|---|
| Is one role accountable for each accounting process? | Procedure owner, job responsibility, or responsibility matrix | Assign an owner and approval authority. |
| Does every material transaction have source documentation? | Invoice, receipt, purchase order, contract, or journal support | Define the required document before posting. |
| Are approval limits reflected in the software workflow? | Approval matrix, user roles, and workflow settings | Align access and routing with written policy. |
| Are reconciliations completed and reviewed on schedule? | Signed reconciliation, exception list, and review date | Set a frequency, reviewer, and escalation rule. |
| Can managers trace corrections and overrides? | Audit log, adjusted entry support, and exception approval | Retain evidence and restrict override access. |
| Are outsourced processes monitored? | Service reports, reconciliations, issue log, and review record | Document what is checked and who follows up. |
The user guide that comes with accounting software explains what the menu options do. It usually does not explain which options produce sound accounting practices for your company. That gap is why accounting policies, procedures, forms, and review routines still matter. They translate accounting rules into daily work.
A strong accounting management system should make routine accounting work easier to perform and easier to review. It should define responsibilities, preserve evidence, control changes, monitor outsourced processes, resolve audit findings, and connect software settings to approved accounting policy.
By understanding the consistent accounting rules and control concepts utilized by accounting software, you can develop more confidence in the information generated by the program. You will also have a deeper appreciation of the importance of accounting policies and procedures for internal control, and you will be able to use the system more effectively to run your company.
Frequently Asked Questions
What Is An Accounting Management System?
An accounting management system is the combination of accounting software, accounting policies, procedures, source documents, controls, and management review practices used to produce reliable accounting information.
How Is An Accounting Management System Different From Accounting Software?
Accounting software records and processes transactions. An accounting management system defines how people authorize, document, review, reconcile, and control those transactions so the software output can be trusted.
Who Maintains An Accounting Management System?
The controller, CFO, accounting department, and relevant department managers usually maintain the accounting management system. Top management remains responsible for providing resources and reviewing performance.
What Controls Should An Accounting Management System Include?
It should include controls for transaction authorization, timing, amount verification, classification, documentation, safeguarding assets, audit resolution, and management review.
Why Do Accounting Policies And Procedures Matter?
Accounting policies and procedures turn accounting rules into repeatable work. They help employees understand what to do, give managers a basis for review, and support auditor expectations for control evidence.