What Are The Most Important Pitfalls to Avoid in a Business Startup?
Launching a business is easier than it once was. Thanks to the internet, a new company can reach a vast number of people without a large storefront or sales force. Building a business startup that can consistently cover its costs, serve customers, and become self-sustainable is much harder.
The most important pitfalls to avoid in a business startup usually begin before the first sale, when planning, pricing, cash discipline, and risk controls are still informal. Enthusiasm is useful, but it cannot replace a thought-out plan, diligence, and hard work.
What Are Business Startup Pitfalls?
Business startup pitfalls are common decisions or omissions that weaken a new company’s ability to survive and grow. They include starting without a business plan, mismanaging finances, choosing a market without validating demand, setting the wrong prices, overlooking insurance, underusing technology, trying to do everything alone, and ignoring competition.
Investing your hard-earned money in a business startup idea always carries risk. You cannot remove every uncertainty, but minimizing the risks is a necessity. Practical business startup advice helps you avoid common mistakes by testing assumptions, planning for cash-flow gaps, and learning from the mistakes of others.
8 Mistakes to Avoid When Starting Your Business
Getting excited about starting your own company is natural. It is also wise to keep a level head. The following eight mistakes can turn a promising idea into an expensive lesson if they are not addressed early.
Having No Business Plan
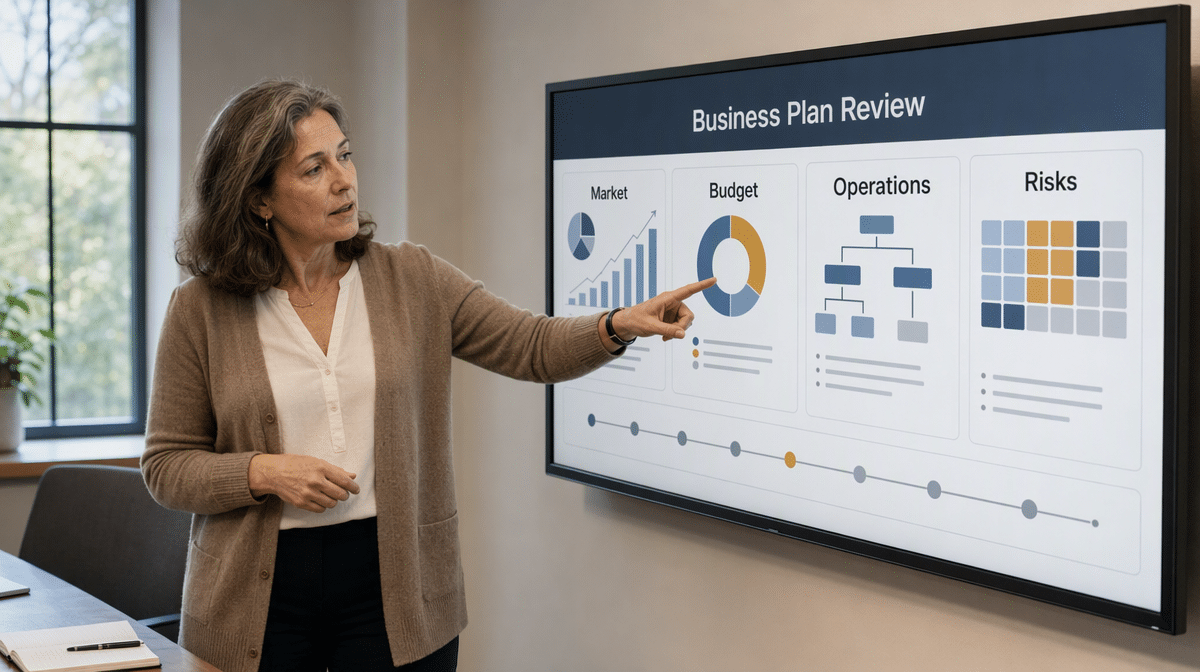
Many small startups begin with an inspirational spark. If the idea is good, that can go a long way. However, you should write a business plan for your startup and consider the many variables that come with running a business. The SBA’s business-plan guidance recommends using the plan as a roadmap for how the company will be structured, operated, and grown.
This is especially important if your business idea is conventional, like a bakery or a common service. What makes your approach stand out? How much competition is in your area? What will it cost to open, and how long will it take to reach a sustainable sales level? A complete plan connects these questions to the myriad business startup requirements that must be funded and managed.
Do some proper research and study the market well before starting the venture. It can be as simple as surveying people in your area, interviewing potential customers, or testing a small offer before committing to a lease. The SBA’s market-research and competitive-analysis guidance highlights demand, market size, saturation, pricing, and competitive advantage as core questions. Evidence from those tests supports the business case that your new startup can be viable.
Not Managing Finances Well
Even a seemingly successful business can fail when it becomes careless with money. Do not reinvest every dollar on a whim or treat revenue as profit. A basic financial plan should show expected startup costs, fixed expenses, variable costs, debt payments, taxes, and the sales level required to cover them.
Begin by learning how to estimate startup costs, then build a rolling cash-flow forecast. Review the forecast against actual results at least monthly. That comparison helps you see whether slow customer payments, rising input costs, or an unexpected demand shock could create a gap before it becomes a crisis.
If you are bootstrapping your startup business, it is even more important to keep money saved as a buffer when cash flow slows. Stabilize the company’s financial security before taking major risks, and define how much cash must remain available before approving discretionary spending.
Choosing a Niche Without Room to Grow
It is a popular business startup strategy to fill a small, unpopulated niche and then dominate it. That can work well, but small niches limit the potential scope of a business by definition. The pitfall is not choosing a niche; it is choosing one without confirming that enough customers have the problem, will pay to solve it, and can be reached at a reasonable cost.
Once you conquer a niche, competition will likely appear out of the woodwork. Before committing, estimate the niche’s practical size, margins, repeat-purchase potential, and likely competitive response. It can be favorable to develop the idea with long-term business prospects in mind. An unusual business to start can still create expanding opportunities when it solves a durable problem and offers logical expansion into adjacent customers, locations, or services.
Pricing Products Too High or Low
Finding the sweet spot regarding prices is an essential part of selling items or services. If you price too high without showing enough value, it might steer off customers. On the contrary, too low a price may raise suspicions that what you are selling is not of quality, while the company may lack enough gross margin to pay its bills and improve the offer.
Your pricing strategy should account for direct costs, overhead, competition, customer psychology, and the value of the outcome. Test pricing with real customers instead of relying on guesswork. Track conversion rate, gross margin, repeat purchases, and customer feedback so that a price change is a measured business decision rather than a reaction to one lost sale.
Avoiding Proper Insurance
Everything is fine until it is not. No founder expects theft, fires, an injury, a vehicle accident, or other unfortunate circumstances. Yet these events and unforeseen hazards can hit a business in major ways when its insurance does not match its actual exposure.
More insurance is not automatically better, but getting proper insurance is an essential safeguard. Appropriate coverage depends on the business’s property, people, contracts, vehicles, products, professional duties, data, and location. Review limits, exclusions, deductibles, and legal or contractual requirements with a licensed insurance professional, then revisit the coverage as the company changes.
Not Taking Advantage of Technology
The internet remains one of the most useful ways for a startup to reach customers, but technology should support the business rather than become a collection of disconnected subscriptions. An excellent website, a clear brand identity on social media, reliable customer communication, secure records, and consistent marketing campaigns can improve potential reach and how work gets done.
Choose systems based on capability, security, fit, support, and total cost. Hire experts where specialized knowledge is needed, and do not simply pick the cheapest services. Document which tool holds each type of information, who owns it, and how work moves between systems. Simple workflow automation can reduce repetitive data entry and missed handoffs, but only after the underlying process is understood.
Trying to Do Everything on Your Own
Running a business requires attention to detail, but it is not a job for one person forever, however clever or committed the founder may be. Trying to carry every task eventually creates bottlenecks and burnout. It also leaves the company dependent on one person’s memory.
Write down recurring work, define the result that good work should produce, and decide what truly requires the founder’s judgment. Using outsourcing for specialized work and automating tasks that are stable and repetitive is a smart way to save time and your sanity. When the workload becomes consistent, determine the first people to hire in a startup based on the heavy work and constraint they will remove, not the title that sounds most impressive.
Ignoring What the Competition Is Doing
Do not turn your head from what the competition is doing. Study how competitors position their offers, serve customers, price packages, and respond to problems. Analyze their mistakes and strengths without copying protected material or imitating every move.
Competitive analysis helps you understand the advantages you already have and the gaps customers still experience. Those findings can shape product priorities, service standards, and honest marketing content. The goal is to make your company more competitive by creating a clearer and more reliable value proposition.
The Most Important Pitfalls to Avoid in a Business Startup
The most important startup mistakes are connected. A weak business plan produces poor financial assumptions. Poor market research leads to the wrong niche or price. Thin cash reserves make every disruption more dangerous, while missing insurance, disconnected technology, founder overload, and weak competitive awareness make recovery harder.
Use this guide as a practical review of your business startup. Write down the assumptions behind the company, test them with customers, monitor cash flow, protect the risks that could threaten survival, and assign work before the founder becomes the bottleneck. These disciplines will not eliminate uncertainty, but they can reduce startup risks in the early stages and give the business more room to grow.
Frequently Asked Questions
What Are Common Business Startup Pitfalls?
Common business startup pitfalls include operating without a business plan, mismanaging cash flow, entering an unvalidated niche, setting weak prices, overlooking insurance, underusing technology, refusing to delegate, and ignoring competition.
Why Does a Startup Need a Business Plan?
A business plan connects the idea to its market, operating model, financial requirements, and growth assumptions. It gives the founder a structured way to test whether the startup can become viable and self-sustainable.
Why Is Cash Flow Important for a New Business?
A profitable sale does not always produce cash in time to pay current bills. A cash-flow forecast and a practical buffer help a startup prepare for slow payments, rising costs, and unexpected interruptions.
How Should a Startup Set Its Prices?
A startup should consider direct costs, overhead, competition, customer psychology, and the value of the outcome. Prices should then be tested against conversion, gross margin, repeat purchases, and customer feedback.
When Should a Founder Delegate or Automate Work?
A founder should delegate or automate work when it is recurring, can be clearly documented, and no longer requires the founder’s unique judgment. The process should be stable before it is automated.