How Do Accounting Systems Work?

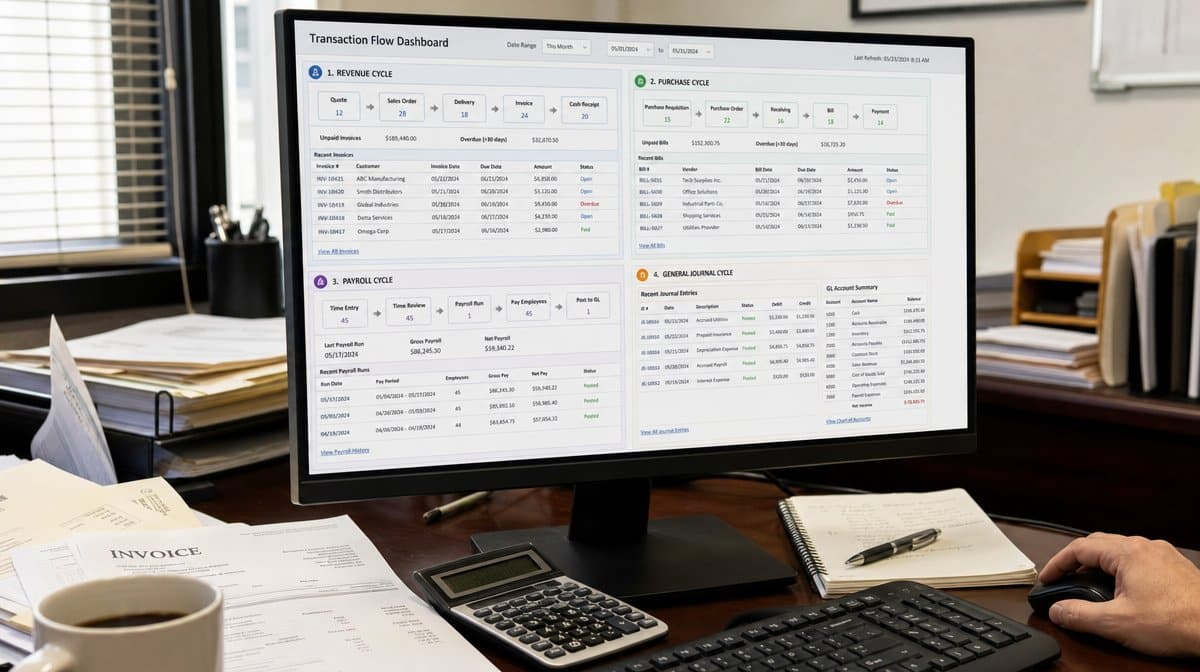
The financial transactions of any accounting system can be grouped into four major accounting cycles: revenue, purchase, payroll, and general journal. Those cycles are where sales invoices, receipts, purchase invoices, checks, payroll entries, and adjusting journal entries enter the books.
Accounting systems work because each source transaction is captured once, routed to the right journal or subsidiary ledger, and then posted to the general ledger. The general ledger, or GL, is the control point that accumulates transaction activity by account class so reports and financial statements can be prepared from organized data.
What Is an Accounting System?
An accounting system is the organized set of records, journals, ledgers, controls, and procedures a business uses to record financial transactions. In a small business, it may be accounting software supported by written procedures and a monthly review process. In a larger organization, it may include separate revenue, purchasing, payroll, inventory, accounts payable, accounts receivable, security, and reporting workflows.
The purpose is the same in either case: record what happened, classify it correctly, preserve a reliable audit trail, and turn daily transaction activity into management reports. The IRS guidance on accounting periods and methods is a reminder that accounting records also need consistency in how income and expenses are reported over time.
Accounting System Cycles
There are four main accounting cycles within most accounting systems: the revenue cycle, purchase cycle, payroll cycle, and general journal cycle. Each cycle has its own source documents and journals, but each eventually connects back to the general ledger.
1. Revenue Cycle
Order Entry. Invoices entered through direct entry, sales orders, or a point-of-sale system are posted to the sales journal. These entries also accumulate on the accounts receivable ledger, organized by customer. If the business maintains inventory, the posting of sales also affects the inventory ledger. Finally, sales journal activity is posted to the GL. A discussion of your revenue cycle should be covered in your revenue procedures.
Cash Receipts and Deposits. Receipts from customers and other bank deposits are posted to the cash receipts journal. Sales receipt information also accumulates on the accounts receivable ledger, organized by customer, and the related cash posting is entered on the bank account ledger. The cash receipts journal is then posted to the GL so cash, receivables, and revenue activity remain aligned.
Accounts Receivable. Accounts receivable, an important part of any accounting system, is a separate ledger that records sales and cash receipt data by customer. The data comes from postings to the cash receipts journal and the sales invoice journal. This separation lets the business see both the total receivable balance and the customer-level detail behind it.
2. Purchase Cycle
Purchase Orders and Purchasing. Invoices entered through direct entry or through purchase orders are posted to the purchase journal. These entries also accumulate on the accounts payable ledger, organized by vendor. If the business maintains inventory, the posting of purchases also affects the inventory ledger. Finally, purchase journal activity is posted to the general ledger.
Cash Disbursements and Checks. Payments on account or payments for expenses are posted to the cash disbursements journal. Payment-on-account information also accumulates on the accounts payable ledger, organized by vendor, and the related cash posting is entered on the bank account ledger. During this cycle of an accounting system, cash disbursement journal activity is posted to the general ledger.
Accounts Payable. Accounts payable is a separate ledger that records purchase and payment activity by vendor. The data comes from postings to the cash disbursements journal and the purchase journal. This lets the business reconcile vendor balances, open bills, payment timing, and total liabilities.
3. Payroll Cycle
During this part of an accounting system, payroll data by employee is entered into the payroll journal. These postings are also entered in the cash disbursements journal and the payroll ledger. Payroll tax liabilities, wage expenses, benefit deductions, and related cash payments must all tie back to the GL so payroll activity can be reported accurately.
4. General Journal Cycle
Corrections or adjustments to the major transaction cycles can be made through adjusting journal entries, posted directly to the general ledger. These are also compiled in a separate journal known as the general journal. Common examples include depreciation, accruals, prepaid expense adjustments, reclassifications, and period-end corrections.
How Does Posting Work?
The specific postings outlined in the cycles above do not necessarily take place as separate manual steps, especially in computerized accounting software systems. There are two basic posting methods in computerized accounting systems: real-time posting and batch posting.
In real-time posting, the source transaction, such as a check, bill, payment, receipt, invoice, or payroll entry, is posted to the specific journal and any related subsidiary ledger. At the same time, it is posted to the general ledger. Real-time posting gives managers faster reporting, but it also requires strong controls over entry, approval, correction, and audit trails.
In batch posting, the journals and subsidiary ledgers are posted first, but entries are not yet posted to the general ledger. Posting those journals to the general ledger is done separately. Typically, a group of transactions, often a full day of work, is entered first. Later, after the journals are reviewed for accuracy, that group, or batch, is posted to the general ledger.
The posting process should be supported by review points. If sales invoices, vendor bills, payroll entries, and bank deposits are entered without review, errors move quickly from source documents into the GL. If the journals are reviewed before posting, the accounting system becomes both a recordkeeping tool and an internal control system.
Accounting Terms and Concepts
To understand how accounting systems work, it helps to define the terms behind the posting process. The accounting system is not just software. It is a structured record of how each business event affects assets, liabilities, equity, revenue, and expenses.
Double-Entry Accounting
We can thank the 14th and 15th century Italian merchants for developing the double-entry system of accounting that businesses still use today. It is widely believed that Benedetto Cotrugli, also known as Benedikt Kotruljevic, was the first to document this concept of double-entry accounting. In 1458, he wrote Delia Mercatura et del Mercante Perfetto, or Of Trading and the Perfect Trader, which included a brief chapter describing many features of double-entry accounting.
In 1494, Luca Pacioli, from San Sepulcro in medieval Tuscany, published the Summa de Arithmetica chapters on bookkeeping, entitled De Computis et Scripturis, or Of Reckonings and Writings. Pacioli helped explain a method traders could use to determine assets and liabilities with greater speed and accuracy.
For many centuries before this, commercial transactions had been recorded, or journalized, on paper, papyrus, or clay tablets. However, those journals often provided only totals of transaction groupings. The Italian merchants recognized that it is impossible for a business transaction to occur without affecting at least two accounts. There can never be only one effect from a transaction. There has to be balance.
There Are Always Two Sides to Every Transaction
An Italian farmer sells wood to a shipbuilder for 400 ducats. To account for this transaction, he would record a wood sale of 400 ducats. His sales account has increased by 400 ducats. But what else happened? His cash account also increased by 400 ducats.
What if he sells his wood to the shipbuilder on credit and receives no cash? In that case, his accounts receivable account increases by 400 ducats. Later, when the shipbuilder pays the debt, the farmer records an increase in cash and a decrease in accounts receivable by 400 ducats each. You can see that an integral feature of the double-entry method is that transactions must equal.
Debits Equal Credits
Bookkeeping entries are divided into debits and credits. The debit side of an accounting system is typically the left side of the ledger page and credits are on the right. The origin of the words debit and credit comes from a simple concept: who owes you, and to whom you owe.
Debits are transactions relating to purchases, expenses, or increases in an organization’s assets. Credits are transactions related to revenues, or an increase in the firm’s equity and liabilities. Recording a transaction requires a debit and a credit entry. If the entries are correctly recorded, the totals on both sides of the ledger agree.
The double-entry bookkeeping method, listing debits in one column and credits in another, requires the debit and credit columns to balance. The method is still the basis for tracking financial affairs, whether the organization uses paper ledgers, desktop accounting software, or a cloud accounting system.
How Does Accounting Management Support the System?
Your Accounting Manuals Template and associated accounting procedures are intended to satisfy documentation requirements for an accounting management system. Department managers and supervisors are responsible for identifying additional documents needed to ensure the effective planning, operation, and control of accounting processes.
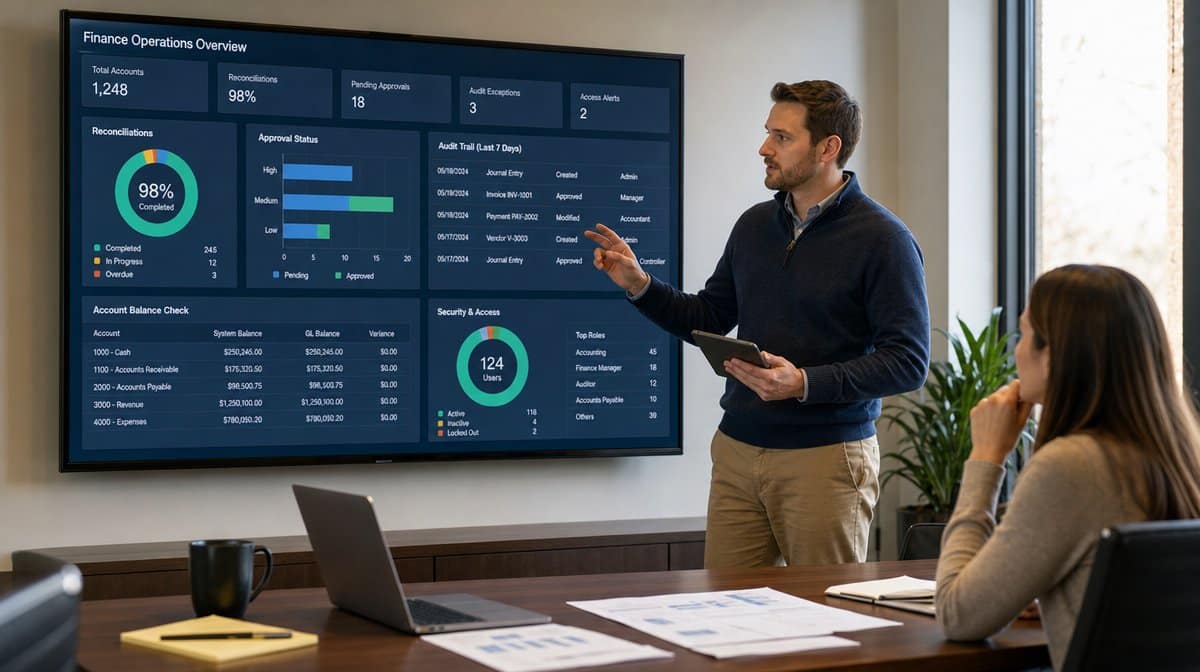
Accounting policies and procedures may vary in detail based on the size of the accounting department or organization involved and the type of activity performed. Accounting procedure writers should consider the complexity of accounting processes and interactions, as well as the competence of accounting personnel. Documents may be any medium, such as paper, digital files, secured records, or controlled templates.
The accounting management system should also support internal control over financial reporting. The SEC has emphasized the importance of risk assessment in financial reporting and internal control decisions, and the same practical idea applies to smaller companies: accounting controls should focus first on the transactions and assets that create the highest risk.
Components of Accounting Management
The structure of the documentation used in the accounting department should be defined, and the authority for establishing that structure should be communicated. Controlled documents should be reviewed and approved before release, and obsolete versions should be removed from routine use.
Accounting records should also be controlled. Records should remain legible, readily identifiable, and retrievable. A documented procedure should define the controls needed for identification, storage, protection, retrieval, retention time, and disposition of records. The Files and Records Management Procedure is an example of the kind of control that supports the accounting system.
Accounting Department Security
Accounting department security has to address physical security, disaster security, information security, and responsibility for company assets. The accounting system contains sensitive information about cash, customers, vendors, employees, bank accounts, and financial performance. Access to those resources should be assigned, maintained, and reviewed.
Accounting Physical Security. Physical security measures should be adopted to protect the assets and employees of the company from abuse, fraud, theft, or damage. Security procedures for the protection of assets and employees are addressed within the company’s Security Manual.
Accounting Disaster Security. Disaster security measures should enable the company to continue operations of the accounting management system with limited interruption. Disaster procedures for operations recovery are addressed within the company’s Disaster Manual.
Accounting Information Security. Information security measures should protect company information assets from unauthorized access, abuse, tampering, theft, or use. Information security procedures for the protection and authorized use of computer and network assets are addressed within the company’s information systems manual. You can also review sample IT policies and procedures.
Frequently Asked Questions
What Are the Four Main Accounting System Cycles?
The four main accounting system cycles are the revenue cycle, purchase cycle, payroll cycle, and general journal cycle. Each cycle captures a different type of transaction activity and posts that activity to the general ledger.
How Does the General Ledger Fit Into an Accounting System?
The general ledger is the central record where transaction activity is organized by account class. Journals and subsidiary ledgers feed the GL so financial statements and management reports can be prepared from a controlled source.
What Is the Difference Between Real-Time and Batch Posting?
Real-time posting updates the journal, subsidiary ledger, and general ledger as the transaction is entered. Batch posting holds a group of entries for review and then posts the batch to the general ledger later.
Why Is Double-Entry Accounting Important?
Double-entry accounting is important because every transaction affects at least two accounts. Requiring debits and credits to balance makes it easier to detect errors and maintain reliable accounting records.
How Do Procedures Improve an Accounting System?
Procedures improve an accounting system by defining who enters, reviews, approves, posts, reconciles, and protects accounting records. Written procedures make controls repeatable instead of dependent on memory or informal habits.