What is the Impact Of Covid-19 On Business Taxation?

COVID-19 turned ordinary tax planning into a cash-flow problem. Businesses that were already managing income loss, remote recruitment, eCommerce sales, and sudden operating restrictions had to understand whether tax relief could create room to keep employees, pay vendors, and stabilize the business.
The impact of COVID-19 on business taxation centered on three major relief areas: temporary net operating loss carrybacks, the Employee Retention Credit, and delayed payment of certain employer payroll taxes. Those provisions were built for the pandemic period, so the practical lesson now is to understand what changed, what expired, and what records still matter.
What Is the Impact of COVID-19 on Business Taxation?
The impact of COVID-19 on business taxation was the way pandemic relief laws changed when businesses recognized losses, claimed payroll credits, deferred tax deposits, and planned for recovery. The U.S. government used tax rules to stabilize the economy amid the pandemic, turning parts of the tax system into a temporary source of liquidity.
In March 2020, business activity across the United States of America slowed sharply as schools, workplaces, and places of trade closed or operated under restrictions. During the pandemic, businesses struggled with income loss and had to rethink tax liabilities alongside payroll, cash flow, and operating procedures.
The problem was not only that revenue fell. The World Bank projected shrinking prospects for much of the global economy, while business owners were trying to keep employees, preserve cash, and understand whether tax rebates or reduced tax obligations could help.
That is why the tax discussion became more than a filing issue. Business owners were faced with adapting to the new way of doing business, including remote recruitment, the rise of eCommerce sales, and evidence that a COVID-19 shutdown could change taxable income before owners had time to plan.
How Did Net Operating Loss Carrybacks Change?
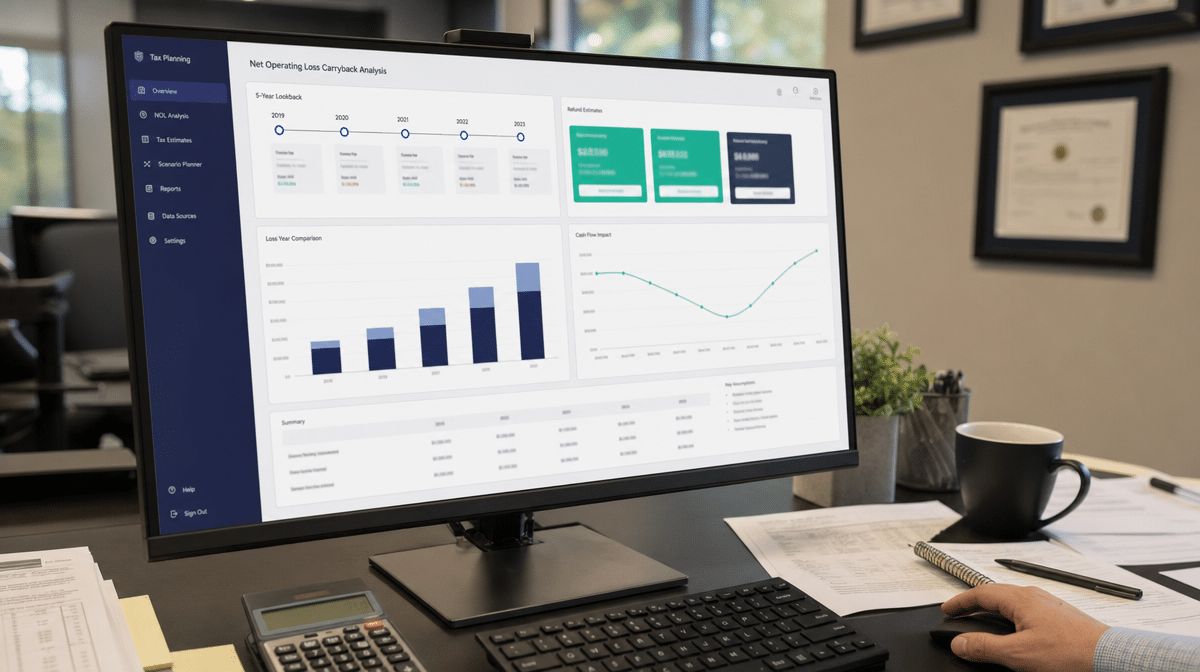
One of the largest COVID tax changes involved net operating losses. Under the CARES Act, certain net operating losses from 2018, 2019, and 2020 could generally be carried back five years, which meant a business with pandemic-period losses could apply those losses against income from earlier profitable years.
That mattered because a carryback can turn a loss year into a cash refund. Instead of only carrying losses forward to reduce future taxable income, eligible businesses could look backward, amend prior-year returns, and potentially recover taxes already paid. The IRS explains this five-year carryback period for 2018, 2019, and 2020 NOLs in its NOL carryback guidance.
In the 2020 relief context, this meant small businesses with losses back as far as the pandemic year could seek relief depending on the year involved. Accounting organizations, accounting firms, and the IRS were offering tailored advice because the rules could minimize the burden for cash-strapped businesses trying to stay afloat.
Why Did the Five-Year Carryback Matter?
Small businesses that lost revenue because of COVID-19 needed cash faster than normal planning cycles could provide it. A SHRM survey reported that 60 percent of small business owners lost revenue because of COVID-19, and 13 percent reported losing 100 percent of their business income.
For those businesses, a five-year carryback could produce tax rebates from profitable years before the pandemic. That relief did not fix the operating problem by itself, but it could improve cash flow at a time when payroll, rent, vendor commitments, and customer demand were all under pressure.
What Happened to the 80 Percent NOL Rule?
The CARES Act also temporarily changed how the 80 percent limitation applied to net operating losses. In broad terms, businesses did not have to limit certain NOL deductions to 80 percent of taxable income for the covered pandemic years, which created another route to faster relief.
Before that pause, a business often had to adhere to limits before carrying forward the remainder of a loss. During the covered period, the ability to offset operating costs against more taxable income in a given year could increase cash flow immediately, rather than forcing the business to wait for a future tax period.
That pause should be treated as a historical COVID provision, not as a standing rule for every later tax year. For post-2020 years, NOL treatment again depends on current tax law, the year the loss arose, ownership changes, and the type of taxpayer. Businesses should preserve source NOL workpapers, amended-return support, and calculations that show why a carryback or carryforward was used.
What Is the Employee Retention Credit?
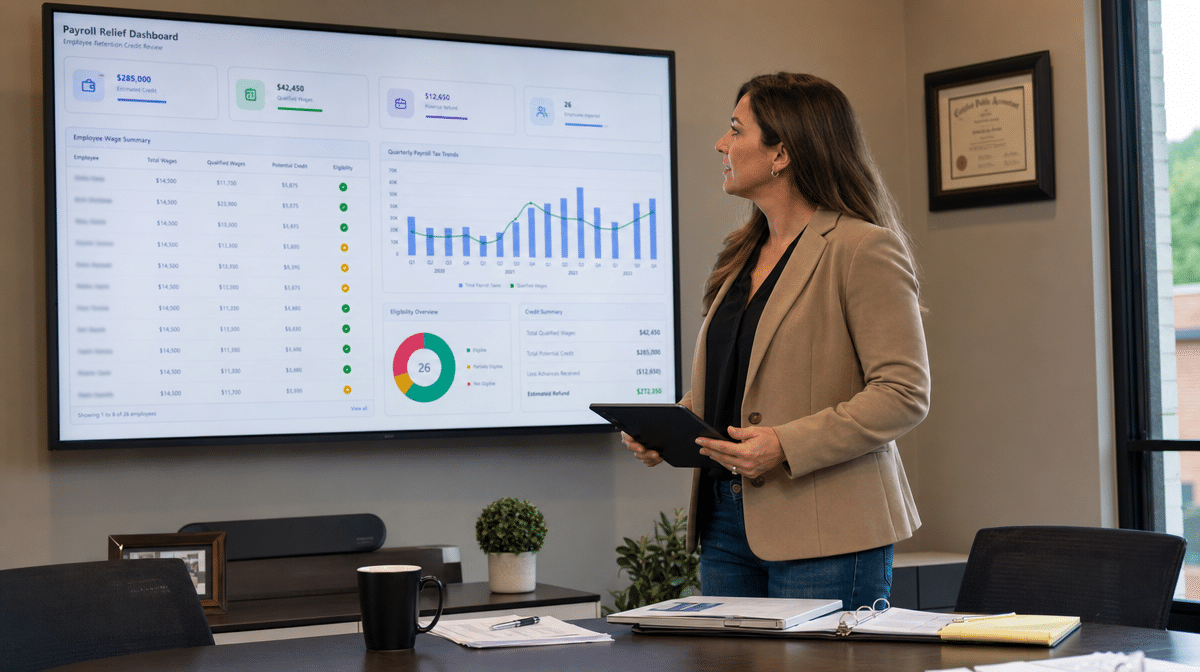
The Employee Retention Credit, often called the ERC or payroll tax credit, was a refundable payroll tax credit created to help employers keep employees during the COVID-19 pandemic. The credit applied to eligible wages and certain health plan expenses paid in covered periods, subject to different rules for 2020 and 2021.
For 2020, the credit generally equaled 50 percent of up to $10,000 in qualified wages per employee for the year. At that time, businesses were still evaluating shutdowns, payroll quarters, revenue loss, healthcare premiums, and Social Security employer tax liability in real time.
The Coronavirus Aid, Relief, and Economic Security Act introduced the credit to give relief to both businesses and employees. The rule was also referred to as a payroll tax credit, and it aimed to help employers that could show they were impacted between March 12, 2020, and the applicable covered periods.
That active relief period has passed, but the ERC still matters because the IRS continues to publish guidance, process claims, and warn employers about improper filings. Businesses reviewing old claims should use the IRS Employee Retention Credit hub as the starting point, not third-party promotional material.
There was also a small caveat in the early relief design: small businesses using a small business interruption loan had to coordinate that loan with payroll tax credit rules. The important point today is the same operational point as in 2020: do not claim a credit without evidence, calculations, and documentation that explain why the business qualified.
What Records Support ERC Eligibility?
ERC eligibility depended on period-specific rules, including government orders, gross receipts, qualified wages, and whether employees were providing services. A business that claimed or reviewed the credit should keep payroll registers, health plan expense support, gross receipts calculations, shutdown-order analysis, and copies of any amended payroll tax returns.
This is where the COVID-19 business taxation issue still has practical force. Even after the emergency period ends, the tax record remains. Businesses need organized accounting files, clear responsibility for payroll tax documentation, and a review process before responding to IRS notices or adjusting old claims.
How Did Payroll Tax Deferral Work?
Businesses were also allowed to delay the deposit and payment of certain employer payroll taxes during 2020. The CARES Act provision focused on the employer share of Social Security tax, which is the 6.2 percent employer tax on covered wages.
The deferral did not erase the tax obligation. It moved the timing. The IRS explained that deferred employer Social Security taxes were generally due in two installments, with 50 percent due by December 31, 2021 and the remaining 50 percent due by December 31, 2022, as described in its employment tax deferral guidance.
At the time, employers were also allowed to hold back deposits that otherwise would have gone to the IRS, which was a bid to preserve liquidity. If an employer chose to defer, the accounting system needed to show the outstanding credit or liability clearly, because relief in the form of a timing change still had to be repaid.
How Did Payroll Tax Deferral Affect Self-Employed Owners?
Self-employed business owners were also part of the payroll-tax relief structure. They could defer part of the Social Security portion of self-employment tax for the covered 2020 period, which gave sole proprietors and other self-employed taxpayers a similar timing benefit.
For accounting purposes, deferral created a liability-management issue. A business could improve short-term liquidity, but it still had to track the repayment dates, maintain payroll tax liabilities in the accounting system, and avoid treating temporary relief as permanent cash.
What Should Businesses Review Now?
COVID-19 tax relief is no longer a new operating surprise, but it can still affect audits, amended returns, financial statements, and documentation. A business that used NOL carrybacks, claimed ERC, delayed payroll tax deposits, or changed payroll tax credits should maintain a clean file showing the decision, the calculation, the tax period, and the supporting records.
The same discipline applies to future disruptions. When a tax law changes quickly, the companies that respond best usually have current books, documented approval workflows, and a finance team that knows where tax compliance and planning records live. That preparation can make the business better prepared for the recovery period after a disruption.
The impact of COVID-19 on business taxation was therefore both immediate and lasting. The immediate impact was relief through NOL carrybacks, payroll tax credits, and deferred deposits. The lasting impact is a reminder that tax obligations, cash flow, and financial controls need to be managed together.
Frequently Asked Questions
How Did COVID-19 Affect Business Taxation?
COVID-19 affected business taxation by creating temporary relief provisions for net operating losses, payroll tax credits, and employer payroll tax deferrals. These rules were designed to improve cash flow during the pandemic period.
What Was the CARES Act NOL Carryback Rule?
The CARES Act generally allowed eligible net operating losses from 2018, 2019, and 2020 to be carried back five years. This gave qualifying businesses a way to seek refunds from prior profitable tax years.
Is the Employee Retention Credit Still Available?
The Employee Retention Credit applies to qualified wages paid during covered COVID-19 periods, not to current wages. Businesses reviewing old claims should rely on current IRS guidance and keep complete payroll and eligibility records.
Did Payroll Tax Deferral Eliminate the Tax?
No. Payroll tax deferral delayed the deposit and payment of certain employer Social Security taxes during 2020. The deferred amounts still had to be tracked and repaid according to IRS deadlines.
What Records Should a Business Keep for COVID-19 Tax Relief?
A business should keep tax returns, amended returns, payroll reports, gross receipts calculations, NOL schedules, ERC support, deferral records, and management approvals. These records explain why relief was claimed and how the amounts were calculated.