What Is Manufacturing Overhead?
A quote goes out at a price that looks healthy on the spreadsheet, the job runs clean, and the month still closes short. The direct materials were right. The direct labor hours were right. What was missing was everything else the plant consumed while that job was on the floor: the supervisor watching the line, the power running the compressors, the wear on the machine, the lubricants nobody bothered to trace.
Manufacturing overhead is the name for those costs, and one reason small manufacturers underprice work is that they have not built a defensible rate for these costs. This article defines manufacturing overhead, shows exactly which factory costs belong in the pool, gives the total factory overhead cost formula, and walks through a complete overhead rate example for one production month that you can adapt to your own plant.
What Is Manufacturing Overhead?
Manufacturing overhead is the total of every indirect production cost a business incurs to operate its factory, excluding direct materials and direct labor. It is also called factory overhead, factory burden, or production overhead. The defining test is not whether the cost is necessary. It is whether the cost can be traced economically to a single unit or job.
Factory rent is necessary, but no invoice tells you how much of April’s rent belongs to Job 412. The same is true of the plant manager’s salary, the electricity bill, and the depreciation on a press that ran forty different part numbers. Those costs are real product costs, so they cannot be ignored, and they cannot be traced, so they must be allocated. Manufacturing overhead is the pool of costs that sits in that gap.
How Manufacturing Overhead Differs From Direct Costs
Direct materials and direct labor attach themselves to a job through ordinary paperwork. A material issue ticket identifies which parts left the stockroom for a work order. A time record identifies which employee spent which hours on a job. Both normally provide a traceable amount without allocating plant-wide costs across jobs.
Overhead produces no such document. It arrives as a monthly bill for the whole plant, so the accounting question changes from what did this job consume to what share of the plant did this job consume. Answering that question with a rate rather than a guess is the entire purpose of overhead allocation, and it is a core topic within cost accounting.
What Counts as Manufacturing Overhead?
A cost belongs in manufacturing overhead when it satisfies two conditions at the same time. It must be incurred inside the production function, and it must be impractical to trace to one unit. Costs that meet both tests include the following.
- Indirect labor. Production supervisors, material handlers, machine setters, quality inspectors, maintenance technicians, and plant schedulers.
- Indirect materials. Lubricants, coolant, abrasives, welding gas, cleaning supplies, and low value fasteners consumed across many jobs.
- Factory occupancy. Rent, property tax, building insurance, and building maintenance for the production space.
- Factory utilities. Electricity, natural gas, water, compressed air, and waste removal serving production.
- Equipment costs. Depreciation, repairs, calibration, tooling, spare parts, and equipment lease payments.
- Production support. Factory software licenses, production planning systems, safety equipment, and required plant training.
Is Depreciation an Overhead Cost?
Depreciation on production equipment and on the factory building is manufacturing overhead. Depreciation on office furniture, sales vehicles, and administrative computers is not. The location and function of the asset decide the answer, not the fact that the entry is a non cash charge.
The reason the distinction matters is that depreciation is a genuine cost recovery mechanism rather than an accounting formality. The Internal Revenue Service describes depreciation as an annual income tax deduction that allows a taxpayer to recover the cost or other basis of property over the time the property is used, as an allowance for wear, deterioration, or obsolescence. Equipment that wears out making your product is consuming value on every job it runs, and the overhead rate is how that value reaches the unit.
What Does Not Belong in the Overhead Pool
For financial reporting, selling costs stay out of inventory, and general and administrative costs are normally period costs. A portion of general and administrative expense that is clearly related to production can be included in inventory cost under the applicable inventory accounting guidance. Tax capitalization follows section 263A and can include some indirect and mixed-service costs, so document the treatment that applies to your business with your tax adviser.
Mixing unrelated selling or administrative costs into manufacturing overhead can inflate inventory values and distort quotes. The reverse error also matters: excluding production-related indirect costs can understate inventory and product cost. Apply the same documented classification policy consistently.
What Is the Total Factory Overhead Cost Formula?
The formula for manufacturing overhead is a sum, not a ratio. Total manufacturing overhead equals indirect labor plus indirect materials plus factory occupancy plus factory utilities plus equipment and depreciation costs plus other indirect production costs for the period.
Two derived figures do the practical work. The predetermined overhead rate equals budgeted manufacturing overhead divided by the budgeted allocation base. Applied overhead for any job equals that rate multiplied by the job’s actual usage of the base. The allocation base is usually direct labor hours, machine hours, or direct labor cost, and the right choice is whichever driver best explains why overhead rises and falls in your plant. Machine hours may better reflect resource consumption in a heavily automated shop, while direct labor hours may be more representative in a labor-intensive assembly operation. Test the selected base against how indirect production costs actually behave.
How Do You Calculate a Predetermined Overhead Rate?
The worksheet below runs the full calculation for one production month at a hypothetical machine shop. The figures are illustrative, but the structure is the one to copy: pool the costs, pick a base, divide, apply the result to a job, then reconcile what you applied against what you actually spent.
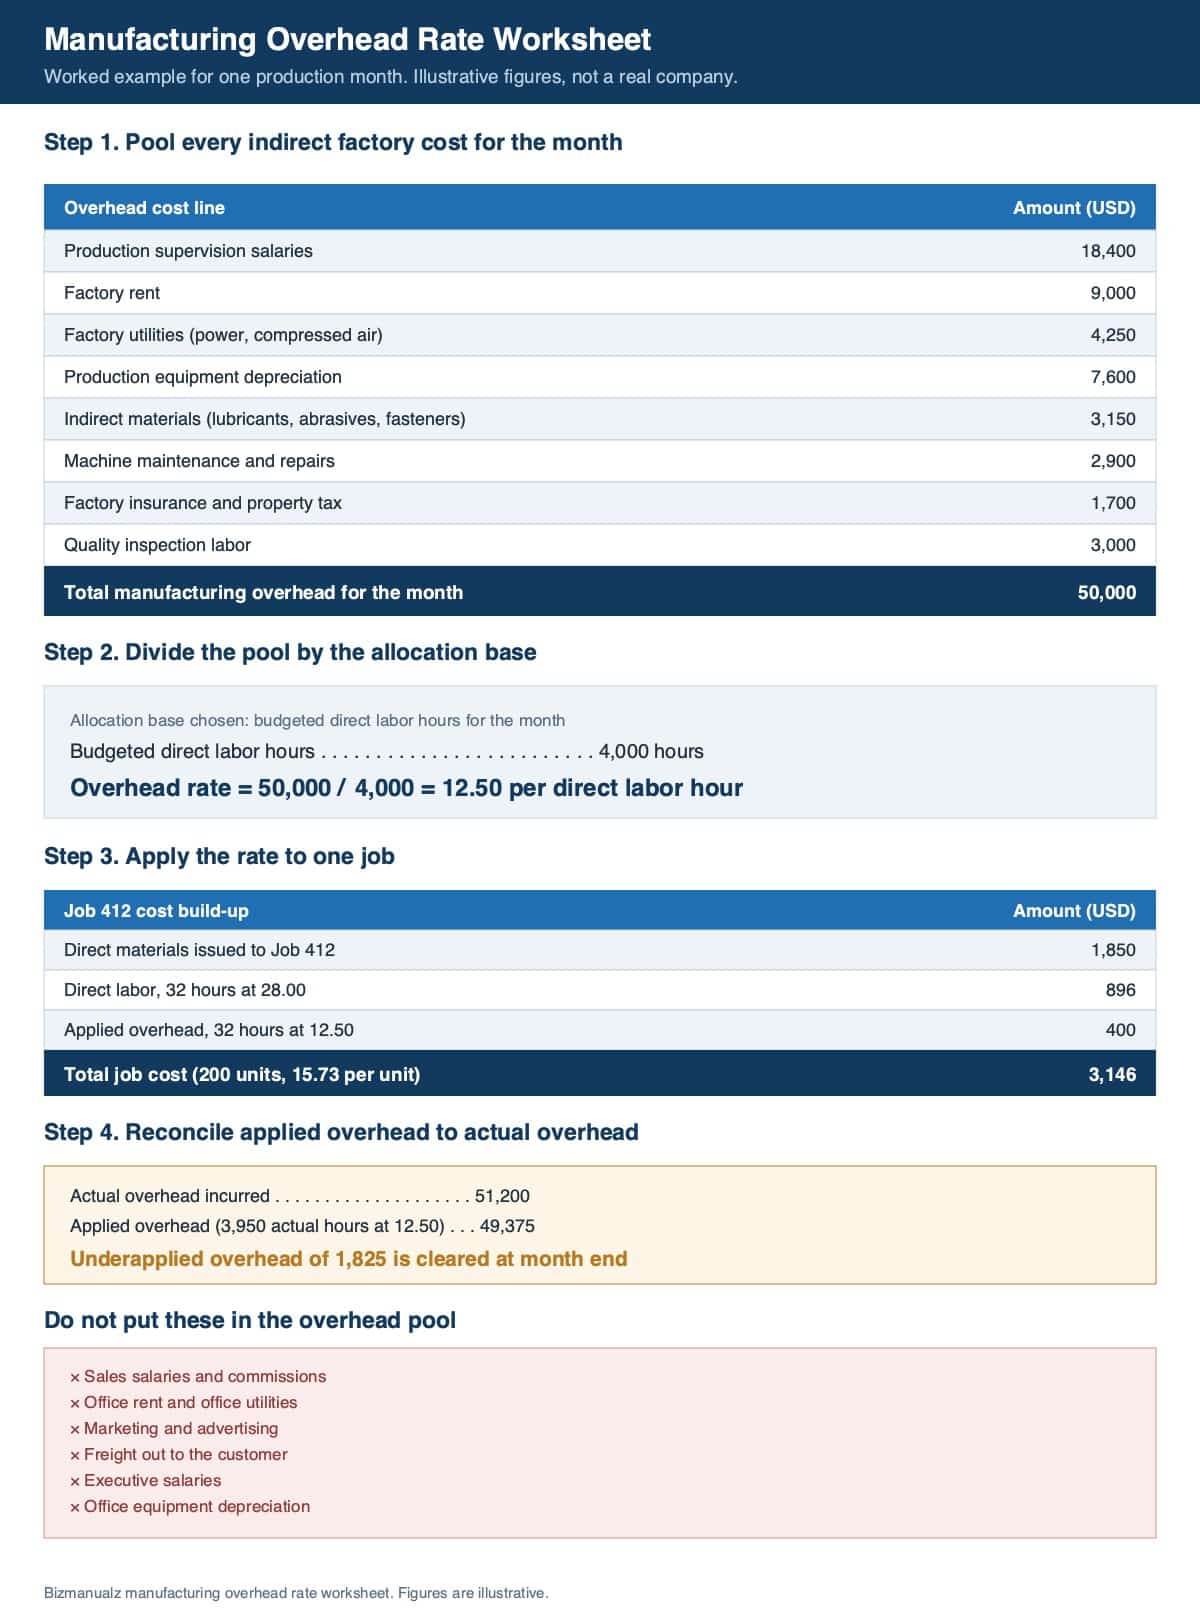
Read the worksheet as four steps.
- Pool the indirect factory costs. Supervision of 18,400, factory rent of 9,000, utilities of 4,250, equipment depreciation of 7,600, indirect materials of 3,150, maintenance of 2,900, factory insurance and property tax of 1,700, and inspection labor of 3,000 total 50,000 for the month.
- Divide by the allocation base. Against 4,000 budgeted direct labor hours, the overhead rate is 50,000 divided by 4,000, or 12.50 per direct labor hour.
- Apply the rate to the job. Job 412 consumed 1,850 of materials and 32 labor hours at 28.00, or 896 of direct labor. Applied overhead is 32 hours multiplied by 12.50, or 400. The job costs 3,146 in total, which is 15.73 across its 200 units.
- Reconcile at month end. Actual overhead came in at 51,200 while applied overhead on 3,950 actual hours was 49,375, leaving 1,825 of underapplied overhead to clear.
Notice what step three would have produced without the rate. A quote built on materials and labor alone prices Job 412 at 2,746 instead of 3,146, an understatement of roughly thirteen percent before a single dollar of margin is added. Repeat that across a year of quoting and the plant looks busy and unprofitable at the same time.
What Is Fixed Manufacturing Overhead?
Fixed manufacturing overhead is the portion of the pool that does not change with production volume inside a relevant range. Factory rent, supervisory salaries, property tax, building insurance, and straight line equipment depreciation behave this way. The plant pays the same rent whether it ships 800 units or 1,600 units in a month.
Variable manufacturing overhead moves with activity. Utilities consumed by running machines, indirect materials, consumable tooling, and overtime for material handlers rise as volume rises. For internal analysis, dividing actual fixed plant cost across fewer actual units makes observed cost per unit rise. For GAAP inventory, however, fixed production overhead is allocated using normal capacity. The amount assigned to each unit is not increased merely because production is abnormally low, and unallocated overhead is expensed in the period. This distinction also explains why a realistic annual allocation base is usually more stable than a rate rebuilt from one slow month. It is part of the same mechanism that makes absorption costing results move with volume.
How Does Manufacturing Overhead Reach Cost of Goods Sold?
Production overhead properly allocated to inventory does not become an expense when the underlying cost is incurred. It travels with the unit through work in process and finished goods, then reaches cost of goods sold when the product sells. Abnormal or unallocated overhead may instead be recognized as a current-period expense.
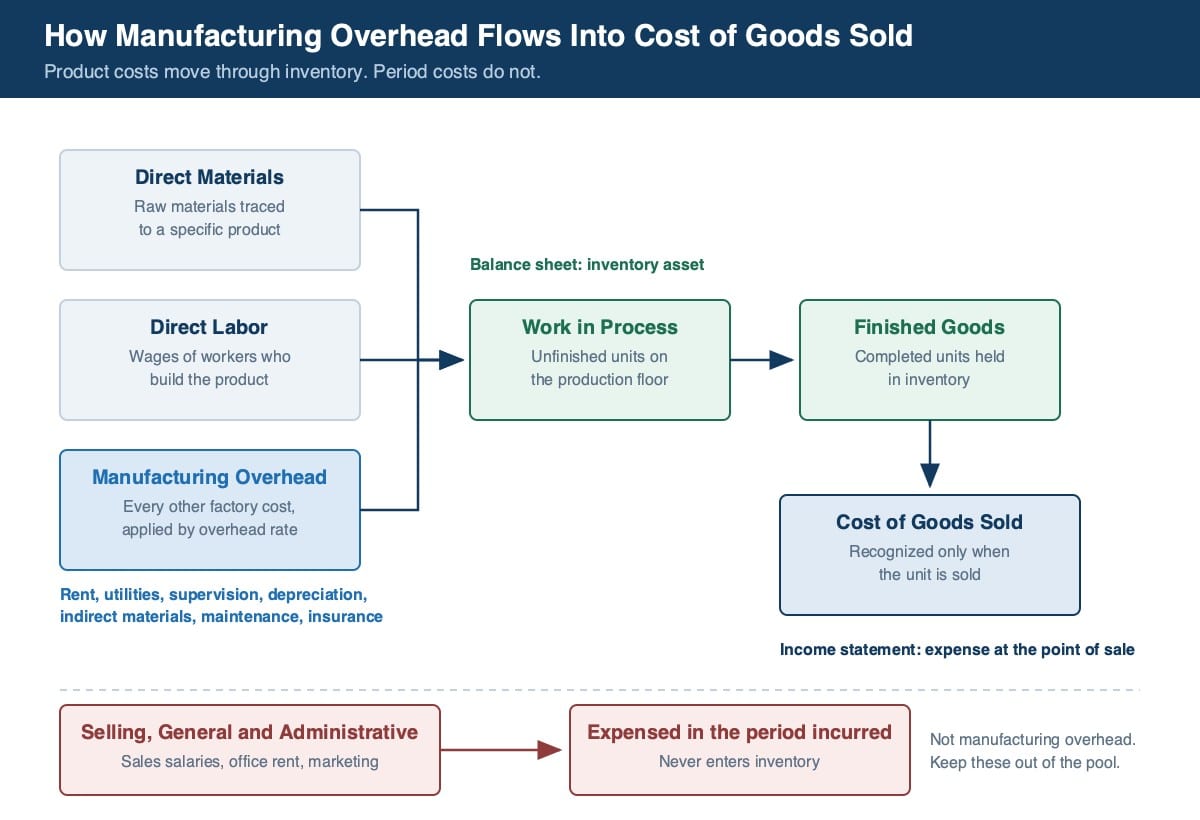
Direct materials, direct labor, and properly allocated manufacturing overhead enter work in process. Completed units move to finished goods, where they sit on the balance sheet as an inventory asset. Only when a unit ships does its full inventory cost move to cost of goods sold on the income statement. Selling costs bypass that path entirely and hit the period in which they occur.
For businesses subject to the uniform capitalization rules, part of the indirect cost of production must be capitalized rather than deducted immediately. The Internal Revenue Service states that you must capitalize the direct costs and part of the indirect costs for production or resale activities, recovering them through depreciation, amortization, or cost of goods sold rather than claiming them as a current deduction. Exceptions exist, including one for a small business taxpayer that meets the gross receipts test under section 448(c) and is not a tax shelter, so confirm your own position with your tax adviser.
Filers of Forms 1120, 1120-C, 1120-F, 1120S, or 1065 that report a cost-of-goods-sold deduction complete and attach Form 1125-A. The form separately identifies additional section 263A costs and other costs, so keep workpapers documenting which accounts feed the overhead pool and how the allocation was calculated.
What Happens When Applied Overhead Does Not Match Actual Overhead?
A predetermined rate is built on estimates, so it rarely matches actual overhead exactly. When actual overhead exceeds applied overhead, the difference is underapplied, meaning jobs were undercosted during the period. When applied exceeds actual, the difference is overapplied and jobs were overcosted.
Subject to the applicable accounting framework and the company’s documented materiality policy, an immaterial variance is commonly closed to cost of goods sold at period end. A material variance may need to be allocated among work in process, finished goods, and cost of goods sold so the remaining inventory and expense balances reflect the period’s production costs. Either way, the size of the variance is a management signal. A persistent underapplied balance usually means the budgeted pool was too low or the plant ran fewer hours than planned, and the rate needs rebuilding rather than patching. Tracking that gap alongside the cost of poor quality often reveals that scrap and rework, rather than the rate itself, are driving the shortfall.
How Should You Document Your Overhead Allocation Method?
An overhead rate that lives in one spreadsheet on one laptop is a single point of failure. A written procedure gives reviewers a consistent record of how the rate was derived instead of relying on one employee’s recollection. Consistency also matters for comparability across periods, which is part of why a business commits to common accounting methods and then applies them the same way every month.
A workable overhead procedure states which accounts feed the pool, which allocation base is used and why, how often the rate is recalculated, who approves a change, how variances are analyzed, and how the treatment ties to the closing entries. Writing that document once removes the annual argument about what belongs where.
The Bizmanualz Accounting Policies and Procedures Manual provides editable, prewritten procedures and forms covering inventory controls, financial reporting, and other core accounting processes. Use them as a starting point, then tailor the procedures to your plant’s accounts, allocation method, approval roles, and close.
Frequently Asked Questions
What Are Manufacturing Overhead Costs?
Manufacturing overhead costs are the indirect production costs of running a factory, excluding direct materials and direct labor. They include indirect labor such as supervision and inspection, indirect materials, factory rent and utilities, equipment depreciation, maintenance, and factory insurance.
How Do You Calculate Total Factory Overhead?
Add the indirect production costs for the period to calculate total factory overhead. To calculate a predetermined overhead rate, divide the budgeted overhead pool by the budgeted allocation base, such as direct labor hours or machine hours. Multiply that rate by each job’s actual use of the base to calculate applied overhead.
Is Depreciation an Overhead Cost?
Depreciation on production equipment and the factory building is manufacturing overhead. Depreciation on office equipment, administrative computers, and sales vehicles is a period cost that stays out of the pool. The function of the asset decides the classification.
What Is Fixed Manufacturing Overhead?
Fixed manufacturing overhead is the part of the pool that does not change with production volume within a relevant range, such as factory rent, supervisory salaries, property tax, and straight line depreciation. For GAAP inventory, fixed production overhead is allocated using normal capacity, so the amount assigned to each unit does not increase merely because production is abnormally low.
What Is a Good Overhead Rate for Manufacturing?
There is no universal benchmark, because the rate depends on automation, wage levels, facility cost, and the allocation base chosen. A labor intensive assembly shop and a highly automated machining operation can both be well run and report very different rates. The useful test is whether the rate is rebuilt from a current pool, applied consistently, and reconciled to actual overhead each period.
Is Manufacturing Overhead an Asset or an Expense?
Production overhead properly allocated to units in work in process or finished goods is part of inventory. It becomes an expense within cost of goods sold when the finished unit is sold. Abnormal or unallocated overhead may be expensed in the period incurred. This treatment affects reported profit as well as inventory accounting values.