How to Manage Business Income Loss During a Pandemic like COVID-19

A pandemic can turn normal business income into a moving target. Customers delay purchases, employees need different work arrangements, vendors change delivery schedules, and the business owner is left trying to protect cash while the rules keep changing.
The goal is not only to survive the immediate income loss. The better goal is to document the loss clearly, preserve options, keep some form of operation alive, and build a recovery plan that can withstand the next disruption.
What Is Business Income Loss During a Pandemic?
Business income loss during a pandemic is the decline in revenue, gross profit, or operating capacity caused by health restrictions, demand shocks, supply interruptions, employee absences, or customer behavior changes. It can show up as fewer orders, canceled contracts, reduced store traffic, higher delivery costs, slower collections, or added safety expenses.
The original COVID-19 lockdown period made this problem visible, but the management discipline is broader than COVID-19. Any prolonged disruption can pressure cash flow, debt service, payroll, inventory, rent, and insurance claims. Treat the event as both a finance problem and a continuity problem.
A business owner should start with a clear operating baseline. Compare current sales, costs, margins, cash receipts, and staffing levels against the last normal period, usually the prior year or a rolling three-year view. That baseline gives you a practical way to estimate the income loss rather than relying on memory or emotion.
How Should You Document Business Income Loss?
Documentation is the difference between a rough complaint and a usable claim, grant application, lender conversation, or management decision. Keep records of daily sales, canceled work, delayed receivables, extra safety expenses, payroll changes, supplier notices, customer communications, and the dates when restrictions affected operations.
If your accounting system allows it, create a separate class, account, or tracking code for pandemic-related losses and recovery costs. That gives finance, ownership, and outside advisors a cleaner view of what changed because of the disruption and what belongs to ordinary business performance.
Evaluating the damages incurred during the COVID-19 pandemic also means deciding what would have happened without the disruption. Create one account or tracking mechanism for pandemic-related losses and a second account for the operating baseline, then compare the last 3 years of business performance with the disrupted period.
You should also document the decisions you made in response. Write down when you reduced hours, shifted to online sales, paused a product line, renegotiated rent, delayed a purchase, or applied for assistance. Those records can support insurance conversations, tax work, bank requests, and internal reviews.
For tax planning, business owners should coordinate with a qualified advisor before assuming how losses will be treated. The IRS explains that a net operating loss can occur when allowable deductions exceed income, but eligibility and use depend on the entity, tax year, and current rules.
Which Funding and Insurance Options Should You Review?
Government grants and disaster programs can help, but they should be treated as one possible source of recovery capital rather than a guaranteed fix. The pandemic period included emergency programs that opened and closed at different times. In a future disruption, state, local, and federal programs may again vary by location, industry, and declared disaster status.
Start with official sources. The U.S. Small Business Administration explains that its disaster assistance can support eligible losses and operating expenses after declared disasters. That does not mean every business qualifies, but it gives owners a reliable place to verify current programs instead of relying on rumors or outdated summaries.
Insurance deserves the same disciplined review. Pull your business interruption, property, civil authority, event cancellation, and general liability policies. Note notice deadlines, exclusions, documentation requirements, waiting periods, deductibles, and whether the policy requires physical damage before income coverage applies.
If you receive assistance, track it separately from normal income. Grants, loans, insurance proceeds, deferred payments, and forgiven balances can affect accounting, taxes, cash-flow forecasts, and future lender conversations. The rebuilding fund is useful only if you know what money came in, what restrictions came with it, and where it went.
Take advantage of grants and funding only after you confirm the current requirements with your local government, lender, or official program administrator. The money may become a rebuilding fund, but the business should still record how it was requested, approved, received, and used.
How Can You Manage Debt and Cash Flow?
Debt management is not only about finding a new loan. It starts with understanding the next 13 weeks of cash: expected receipts, payroll, rent, inventory commitments, tax obligations, debt payments, and any expenses needed to keep operations viable.
If you have multiple debts, ask lenders about hardship programs, payment deferrals, maturity extensions, covenant relief, or refinancing. Debt consolidation may help in some cases, but it should be reviewed carefully because a lower payment can come with a longer term, new fees, collateral requirements, or a higher total cost.
Some owners choose a consolidation loan or refinancing option to put multiple debts into one repayment scheme. That can reduce pressure when the new terms offer a lesser interest rate or lower monthly payment, but acquiring debt during a disruption should be compared against fees, collateral, term length, and the value of keeping extra money in an emergency fund.
Prioritize cash uses by business continuity. Payroll needed to serve customers, inventory tied to near-term demand, core systems, insurance, and essential vendors usually rank higher than discretionary purchases. If a payment cannot be made on time, communicate early and document the agreement.
Internal controls still matter during a crisis. A rushed recovery can create duplicate payments, weak approvals, missing receipts, and unclear authority. Finance policies, spending limits, and approval procedures help the business move quickly without losing control of the cash it has left.
How Can You Keep Operations Running?
Do not totally shut down your business unless the facts require it. A partial operating model can keep revenue alive, preserve customer relationships, and keep employees connected to the business. For some companies that means online ordering, curbside pickup, remote service, appointment-only work, limited production, or a narrower product mix.
The question is not whether the old operating model can continue unchanged. The question is which profitable pieces can continue safely and legally while the business rebuilds. Review customer demand, local restrictions, employee availability, supplier reliability, and the minimum staffing needed to fulfill promises.
If you are selling a product, the online marketplace can keep the business visible even when a physical store is limited. After restrictions ease, the online shop can continue alongside the physical store and may help you reach more customers locally and overseas.
You should also check whether your industry is allowed to run under specific guidelines and restrictions. If the answer is unclear, ask the responsible authority whether the business can operate by following proper guidelines rather than assuming a total shutdown is required.
Technology can help, but only when it supports a specific workflow. Online sales, digital invoicing, remote approvals, shared files, video meetings, and customer notifications can reduce friction. Avoid adding tools that create more work than they remove.
If you move work online, update the process around it. Document who receives orders, who approves refunds, who contacts customers, who reviews cash receipts, and who monitors service failures. A fast workaround becomes a business process only when people know how to repeat it.
Why Should You Create a Recovery Team?
Being proactive requires ownership. Create a small recovery team that includes leadership, finance, operations, human resources, and a customer-facing employee. The team does not need to be large, but it needs enough authority to identify problems and make recommendations quickly.
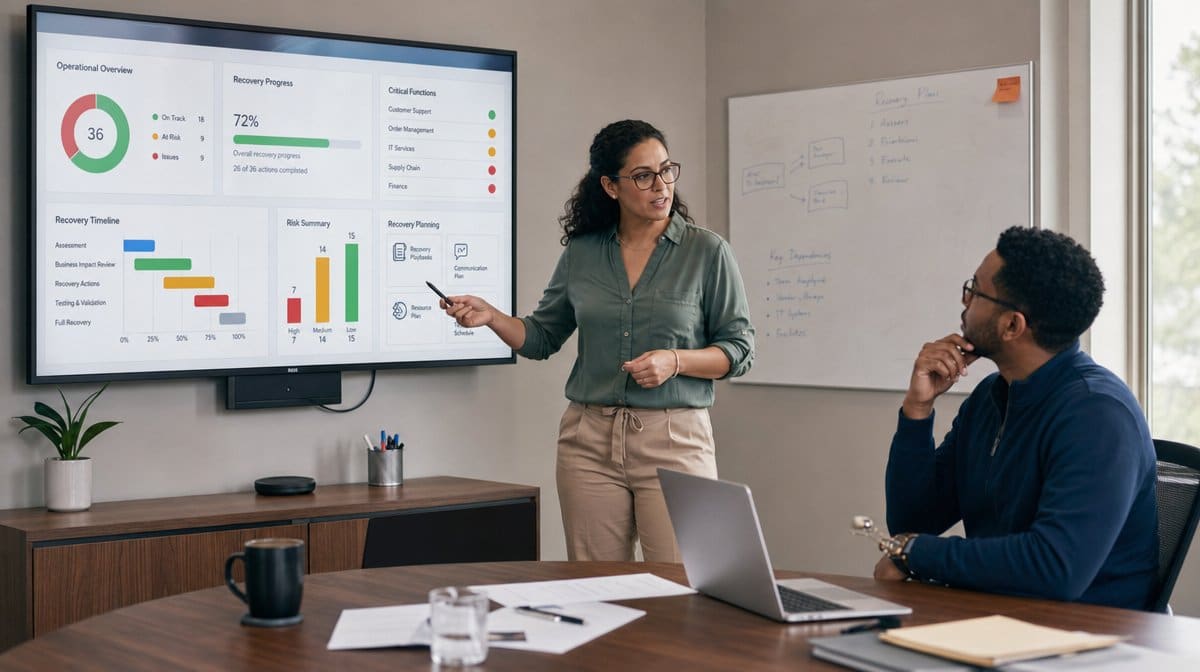
The recovery team should meet on a set cadence, review cash, document losses, track funding applications, monitor employee availability, evaluate operating changes, and keep a running action list. The team should also own communication so employees and customers do not receive conflicting messages.
The recovery team keeps motivation focused on achievable actions instead of vague optimism. It can study options, research new ways to reach customers, find innovative operating methods, and push the company toward a stronger version of the business.
Human resources should be involved early. A pandemic-style disruption affects staffing, leave, scheduling, remote work, safety communication, and morale. Clear HR policies help employees understand what the company can offer, what it expects, and how decisions will be made.
The best recovery teams also capture lessons while the pressure is fresh. Which vendors failed? Which customers stayed? Which products remained profitable? Which procedures were unclear? Those answers turn an emergency response into a stronger continuity plan.
Takeaway
Managing business income loss during a pandemic like COVID-19 requires more than cutting costs. You need a documented loss record, a disciplined cash plan, current information on assistance and insurance, a practical operating model, and a team responsible for recovery decisions.
A business that records its losses, manages debts carefully, keeps some operation alive, and updates its continuity procedures is in a stronger position to reopen, rebuild, and withstand the next disruption.
Frequently Asked Questions
What Is Business Income Loss During a Pandemic?
Business income loss during a pandemic is the revenue decline, added expense, and operating disruption a company suffers when normal demand, staffing, supply, or physical access is interrupted. The loss may affect cash flow, payroll, debt payments, inventory, and the ability to reopen at full capacity.
How Should a Business Document Pandemic Income Loss?
A business should document income loss with sales reports, bank statements, invoices, payroll records, insurance notices, grant records, and a written timeline of the disruption. Separate tracking accounts or classes can help show which losses came from the pandemic event and which came from normal operations.
Can Government Assistance Cover Business Income Loss?
Government assistance may help with eligible disaster losses or operating expenses, but each program has its own application window, documentation rules, and repayment terms. Business owners should verify current SBA, state, and local programs before making cash-flow assumptions.
Why Should a Business Keep Operating If Revenue Falls?
A partial operating model can preserve customer relationships, keep staff engaged, and create a bridge to recovery. Online ordering, remote service, limited production, or appointment-based operations may help the business avoid a complete shutdown while conditions improve.
Who Should Manage Business Recovery Planning?
A recovery team should include leadership, finance, operations, human resources, and customer-facing staff. The team should review losses, prioritize cash, communicate with employees, and update the continuity plan as new information arrives.